by Jason Bodner
October 13, 2026
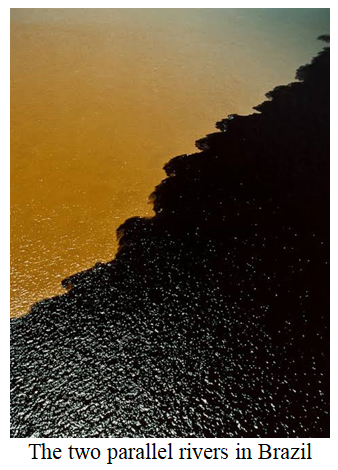
Near Manaus, Brazil, two-giant rivers meet but they don’t mix. The Rio Negro is as dark as black coffee, warm, and slow, while the Solimões is sandy, cool, and moves two or three times faster. For about 3.75-miles, they flow side by side in the same channel, with a line between them so stark you can see it from space. The two parallel rivers don’t fully blend until about 38-miles downstream.
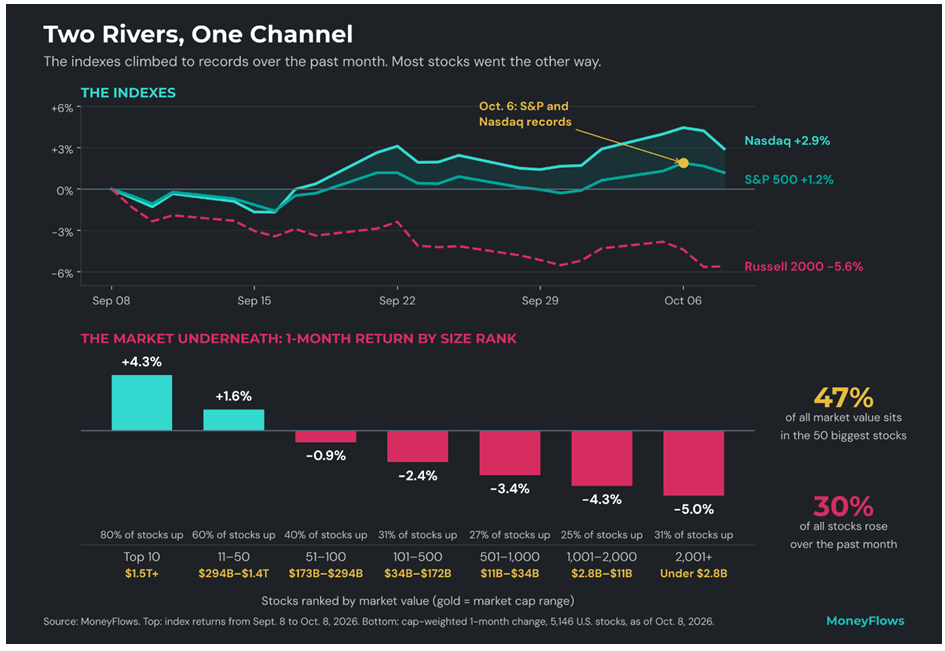
That’s the stock market right now: two-rivers in one channel. The big cap-weighted indexes are one river, rising fast, the river of smaller stocks is the other, trailing badly. On Tuesday, October 6, the S&P 500 closed at a record 7,818.93 and NASDAQ hit a record too, but the market underneath has been running cold.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Last Tuesday was also the best day for the underneath market in several weeks. In my recent columns, I flagged October 6 as a likely target date for the low in the market under the indexes, and October 6 indeed fit my script. Outflows dropped to 78, the lightest day since selling began on September 9. ETF outflows (3) nearly vanished. Stocks were climbing out of bear territory from the top of the cap ladder down.
Then the bond market spoke up.
On Wednesday, the 10-year Treasury yield touched 5.35%, its highest level since 2002. The 30-year rate hit 5.70%. On Thursday, a report questioning OpenAI’s revenue numbers spanked the chip stocks, and the NASDAQ fell 1.25%, and then oil jumped 3.6% on the new attacks on shipping near the Strait of Hormuz.
Outflows responded, spiking back to 186 on Wednesday. By Thursday, 253 stocks hit new 52-week lows. But on the same day 154-stocks hit new 52-week highs! The equal-weight S&P actually rose 0.6% while the NASDAQ fell. That’s not a panicking market. That’s two-rivers moving at different speeds.
So, will October 6 remain the low mark? I think it was the turn, and this week will likely see a retest. Lows rarely come in one clean day. Small-caps never got repaired, and everything else gave some back.
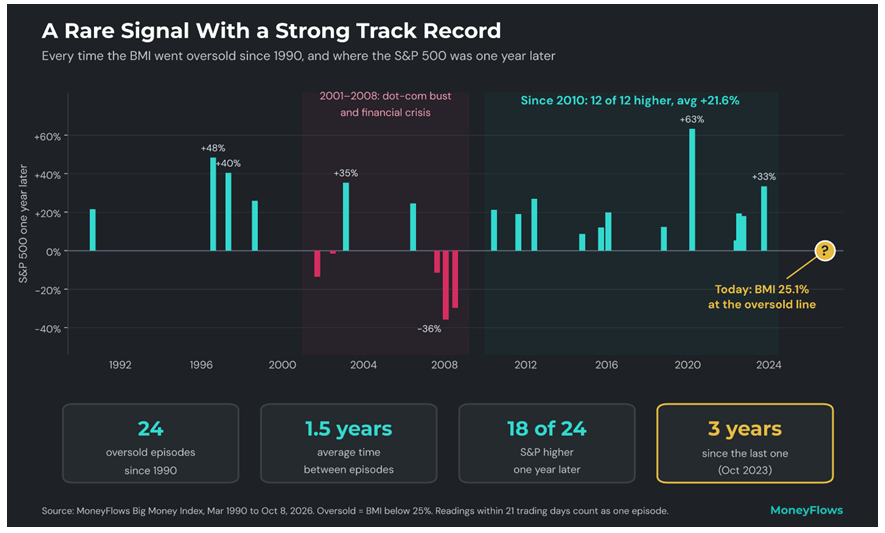
Our Big Money Index (BMI) closed at 25.1%, essentially at our 25% oversold line. This is a rare event. The BMI has never been this low with the S&P within 2% of its high. Since 1990, the closest an oversold reading came was in April 1997, with the S&P 5.3% below its high. A year later, the S&P was up 40%.
Reaching 25% (oversold) itself is uncommon. Since 1990, the BMI has gone oversold just 24-times, about once every 18-months. The last time it fell to 25% was October 2023, three-years ago.
What’s next? In all 24-past episodes, the S&P was higher a year later (75% of the time), averaging +15%. When the S&P was within 10% of its high, it was higher a year later 90% of the time, averaging +22%.
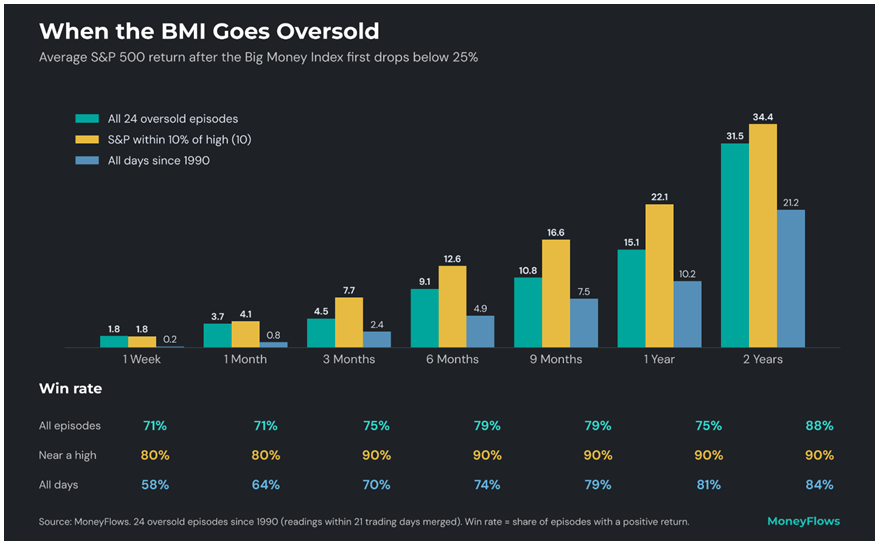
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Since 2010, the track record is clearer. In 12-episodes, the S&P and Dow were higher six-months, nine-months, one-year and two-years later every single time. The NASDAQ averaged 27% gains a year later. Almost every loss came from a troubled time, from 2001 to 2008, during two-deep bear markets.
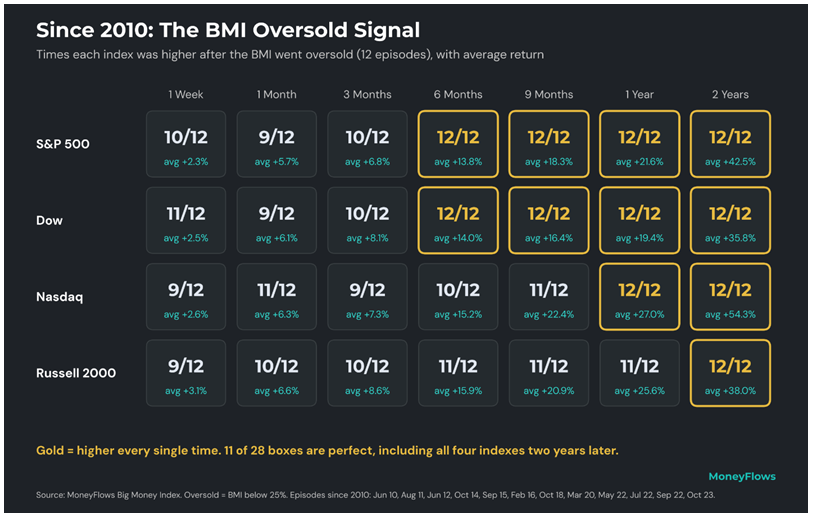
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
It doesn’t usually last long, either. The median stay in oversold territory is about eight-trading days, and the S&P usually bottoms first. If history holds, the BMI revives around October 20, a week from now:
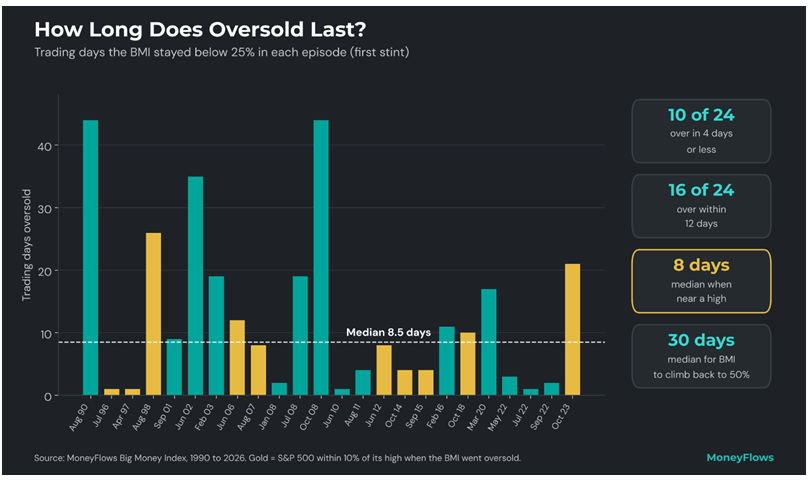
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Now look at the selling itself. Since September 9th, we’ve averaged 158 outflows per day. That’s a storm.
Since 1990, there have been 229-days with selling that heavy, grouped into 16-separate episodes. The S&P 500 forward returns were strongly positive out the curve from 1 week to 2-years out.
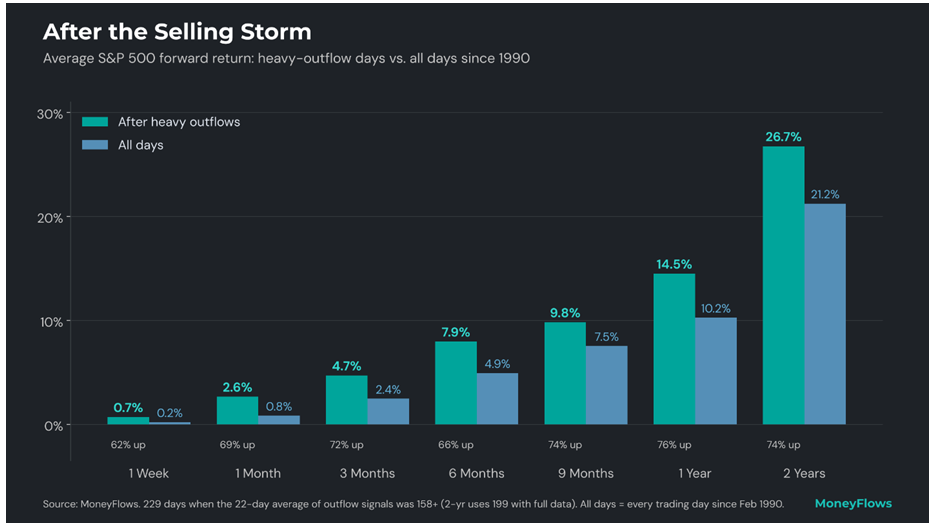
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
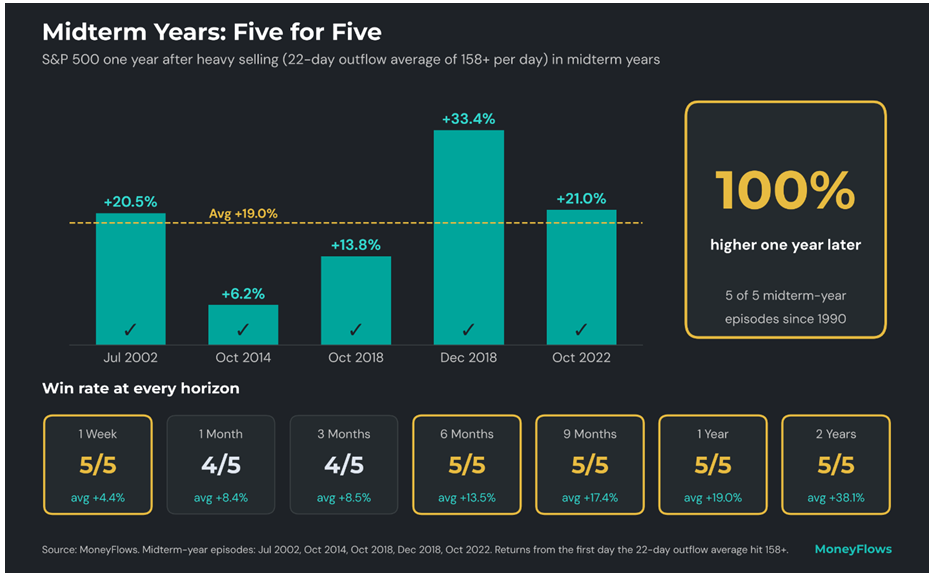
And here’s the midterm kicker. Five of these episodes happened in midterm years: 2002, 2014, 2018 (twice) and 2022. The S&P was higher a year later each time, by an average of 19%.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
What Sectors Are Leading Now – and in the Future?
Now for the sectors, because the selling had a clear target – sell anything that hates higher rates.
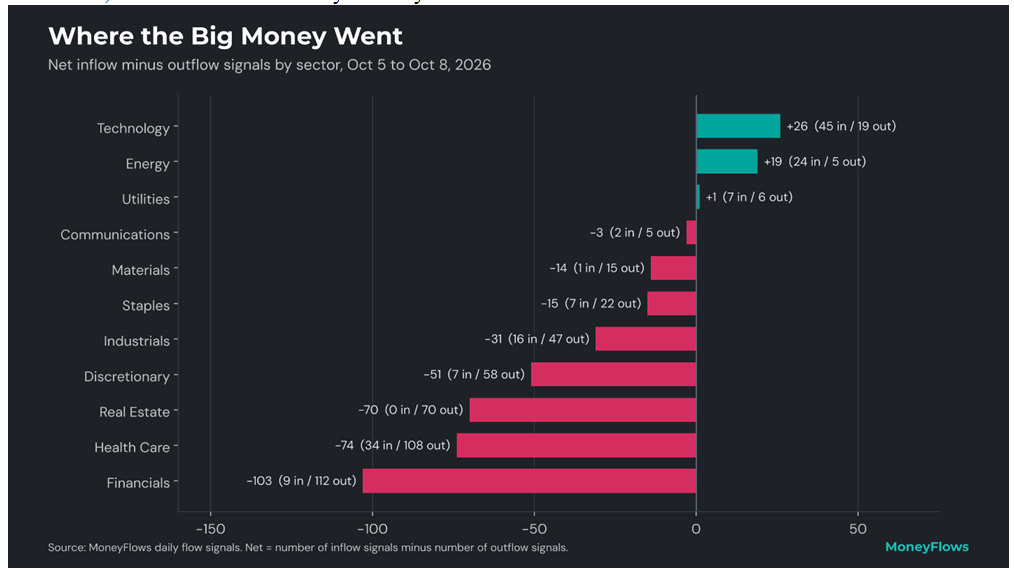
Financials took the heaviest hit, with 112 outflows against just nine inflows. This wasn’t small-town banks. Big Wall Street banks, Canadian banks and private credit managers all showed up on the sell side. Higher long-term rates squeeze lending and raise worries about bad loans.
Health care was next with 108 outflows, led by big drug makers. Real estate saw 70 outflows and zero inflows. REITs borrow heavily and compete with bonds for income buyers, so a 5% 10-year is a direct threat. Discretionary saw 58 outflows, mostly homebuilders and restaurants. With 30-year mortgage rates near 7.5%, homebuilders feel every tick in yields.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Technology saw 45 inflows and energy drew 24. The technology buying was focused on quality: Twenty of the 35-technology names with inflows sat within 5% of their highs. Big money isn’t fleeing stocks. It’s trading weaker balance sheets for stronger ones.
This fits what my colleague Alec Young wrote this week in “Buy Stocks into Rate Hikes.” He says the reasons for rate hikes matter more than the hikes themselves. Today, the Fed is leaning against strong growth and record earnings. He also notes the Mag 7 earn 31.9-times their interest costs, while small caps earn just 1.4-times theirs. Rising rates barely dent one group and squeeze the other.
So, here’s where I stand. The indexes and the market underneath are flowing side by side and not mixing very well yet. Rates provide the wall between the two rivers. October 6 looks like the turn under the surface, and this week is the test. The BMI is nearly oversold with the S&P near a record, which has never happened. History says that’s one of the strongest buy signals in our data, especially in midterm years.
The rivers always mix eventually. Downstream, it all becomes like the Amazon (the river, not the stock).
As Heraclitus said, “No man ever steps in the same river twice.”
All content above represents the opinion of Jason Bodner of Navellier & Associates, Inc.
Also In This Issue
A Look Ahead by Louis Navellier
France is Falling Apart – Is the EU Next?
Income Mail by Bryan Perry
What Will (or Won’t) Generate A Bullish Year End Rally
Growth Mail by Gary Alexander
U.S. Growth is Better than Expected… But Debt is Worse
Global Mail by Ivan Martchev
More New Highs for Stocks
Sector Spotlight by Jason Bodner
The Market Resembles Two Rivers – Light and Dark – Running in Tandem
View Full Archive
Read Past Issues Here
Important Disclosures:
Jason Bodner is a co-founder and co-owner of Mapsignals. Mr. Bodner is an independent contractor who is occasionally hired by Navellier & Associates to write an article and or provide opinions for possible use in articles that appear in Navellier & Associates weekly Market Mail. Mr. Bodner is not employed or affiliated with Louis Navellier, Navellier & Associates, Inc., or any other Navellier owned entity. The opinions and statements made here are those of Mr. Bodner and not necessarily those of any other persons or entities. This is not an endorsement, or solicitation or testimonial or investment advice regarding the BMI Index or any statements or recommendations or analysis in the article or the BMI Index or Mapsignals or its products or strategies.
Although information in these reports has been obtained from and is based upon sources that Navellier believes to be reliable, Navellier does not guarantee its accuracy and it may be incomplete or condensed. All opinions and estimates constitute Navellier’s judgment as of the date the report was created and are subject to change without notice. These reports are for informational purposes only and are not a solicitation for the purchase or sale of a security. Any decision to purchase securities mentioned in these reports must take into account existing public information on such securities or any registered prospectus.To the extent permitted by law, neither Navellier & Associates, Inc., nor any of its affiliates, agents, or service providers assumes any liability or responsibility nor owes any duty of care for any consequences of any person acting or refraining to act in reliance on the information contained in this communication or for any decision based on it.
Past performance is no indication of future results. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. It should not be assumed that any securities recommendations made by Navellier. in the future will be profitable or equal the performance of securities made in this report. Dividend payments are not guaranteed. The amount of a dividend payment, if any, can vary over time and issuers may reduce dividends paid on securities in the event of a recession or adverse event affecting a specific industry or issuer.
None of the stock information, data, and company information presented herein constitutes a recommendation by Navellier or a solicitation to buy or sell any securities. Any specific securities identified and described do not represent all of the securities purchased, sold, or recommended for advisory clients. The holdings identified do not represent all of the securities purchased, sold, or recommended for advisory clients and the reader should not assume that investments in the securities identified and discussed were or will be profitable.
Information presented is general information that does not take into account your individual circumstances, financial situation, or needs, nor does it present a personalized recommendation to you. Individual stocks presented may not be suitable for every investor. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. Investment in fixed income securities has the potential for the investment return and principal value of an investment to fluctuate so that an investor’s holdings, when redeemed, may be worth less than their original cost.
One cannot invest directly in an index. Index is unmanaged and index performance does not reflect deduction of fees, expenses, or taxes. Presentation of Index data does not reflect a belief by Navellier that any stock index constitutes an investment alternative to any Navellier equity strategy or is necessarily comparable to such strategies. Among the most important differences between the Indices and Navellier strategies are that the Navellier equity strategies may (1) incur material management fees, (2) concentrate its investments in relatively few stocks, industries, or sectors, (3) have significantly greater trading activity and related costs, and (4) be significantly more or less volatile than the Indices.
ETF Risk: We may invest in exchange traded funds (“ETFs”) and some of our investment strategies are generally fully invested in ETFs. Like traditional mutual funds, ETFs charge asset-based fees, but they generally do not charge initial sales charges or redemption fees and investors typically pay only customary brokerage fees to buy and sell ETF shares. The fees and costs charged by ETFs held in client accounts will not be deducted from the compensation the client pays Navellier. ETF prices can fluctuate up or down, and a client account could lose money investing in an ETF if the prices of the securities owned by the ETF go down. ETFs are subject to additional risks:
- ETF shares may trade above or below their net asset value;
- An active trading market for an ETF’s shares may not develop or be maintained;
- The value of an ETF may be more volatile than the underlying portfolio of securities the ETF is designed to track;
- The cost of owning shares of the ETF may exceed those a client would incur by directly investing in the underlying securities and;
- Trading of an ETF’s shares may be halted if the listing exchange’s officials deem it appropriate, the shares are delisted from the exchange, or the activation of market-wide “circuit breakers” (which are tied to large decreases in stock prices) halts stock trading generally.
Grader Disclosures: Investment in equity strategies involves substantial risk and has the potential for partial or complete loss of funds invested. The sample portfolio and any accompanying charts are for informational purposes only and are not to be construed as a solicitation to buy or sell any financial instrument and should not be relied upon as the sole factor in an investment making decision. As a matter of normal and important disclosures to you, as a potential investor, please consider the following: The performance presented is not based on any actual securities trading, portfolio, or accounts, and the reported performance of the A, B, C, D, and F portfolios (collectively the “model portfolios”) should be considered mere “paper” or pro forma performance results based on Navellier’s research.
Investors evaluating any of Navellier & Associates, Inc.’s, (or its affiliates’) Investment Products must not use any information presented here, including the performance figures of the model portfolios, in their evaluation of any Navellier Investment Products. Navellier Investment Products include the firm’s mutual funds and managed accounts. The model portfolios, charts, and other information presented do not represent actual funded trades and are not actual funded portfolios. There are material differences between Navellier Investment Products’ portfolios and the model portfolios, research, and performance figures presented here. The model portfolios and the research results (1) may contain stocks or ETFs that are illiquid and difficult to trade; (2) may contain stock or ETF holdings materially different from actual funded Navellier Investment Product portfolios; (3) include the reinvestment of all dividends and other earnings, estimated trading costs, commissions, or management fees; and, (4) may not reflect prices obtained in an actual funded Navellier Investment Product portfolio. For these and other reasons, the reported performances of model portfolios do not reflect the performance results of Navellier’s actually funded and traded Investment Products. In most cases, Navellier’s Investment Products have materially lower performance results than the performances of the model portfolios presented.
This report contains statements that are, or may be considered to be, forward-looking statements. All statements that are not historical facts, including statements about our beliefs or expectations, are “forward-looking statements” within the meaning of The U.S. Private Securities Litigation Reform Act of 1995. These statements may be identified by such forward-looking terminology as “expect,” “estimate,” “plan,” “intend,” “believe,” “anticipate,” “may,” “will,” “should,” “could,” “continue,” “project,” or similar statements or variations of such terms. Our forward-looking statements are based on a series of expectations, assumptions, and projections, are not guarantees of future results or performance, and involve substantial risks and uncertainty as described in Form ADV Part 2A of our filing with the Securities and Exchange Commission (SEC), which is available at www.adviserinfo.sec.gov or by requesting a copy by emailing info@navellier.com. All of our forward-looking statements are as of the date of this report only. We can give no assurance that such expectations or forward-looking statements will prove to be correct. Actual results may differ materially. You are urged to carefully consider all such factors.
FEDERAL TAX ADVICE DISCLAIMER: As required by U.S. Treasury Regulations, you are informed that, to the extent this presentation includes any federal tax advice, the presentation is not written by Navellier to be used, and cannot be used, for the purpose of avoiding federal tax penalties. Navellier does not advise on any income tax requirements or issues. Use of any information presented by Navellier is for general information only and does not represent tax advice either express or implied. You are encouraged to seek professional tax advice for income tax questions and assistance.
IMPORTANT NEWSLETTER DISCLOSURE:The hypothetical performance results for investment newsletters that are authored or edited by Louis Navellier, including Louis Navellier’s Growth Investor, Louis Navellier’s Breakthrough Stocks, Louis Navellier’s Accelerated Profits, and Louis Navellier’s Platinum Club, are not based on any actual securities trading, portfolio, or accounts, and the newsletters’ reported hypothetical performances should be considered mere “paper” or proforma hypothetical performance results and are not actual performance of real world trades. Navellier & Associates, Inc. does not have any relation to or affiliation with the owner of these newsletters. There are material differences between Navellier Investment Products’ portfolios and the InvestorPlace Media, LLC newsletter portfolios authored by Louis Navellier. The InvestorPlace Media, LLC newsletters contain hypothetical performance that do not include transaction costs, advisory fees, or other fees a client might incur if actual investments and trades were being made by an investor. As a result, newsletter performance should not be used to evaluate Navellier Investment services which are separate and different from the newsletters. The owner of the newsletters is InvestorPlace Media, LLC and any questions concerning the newsletters, including any newsletter advertising or hypothetical Newsletter performance claims, (which are calculated solely by Investor Place Media and not Navellier) should be referred to InvestorPlace Media, LLC at (800) 718-8289.
Please note that Navellier & Associates and the Navellier Private Client Group are managed completely independent of the newsletters owned and published by InvestorPlace Media, LLC and written and edited by Louis Navellier, and investment performance of the newsletters should in no way be considered indicative of potential future investment performance for any Navellier & Associates separately managed account portfolio. Potential investors should consult with their financial advisor before investing in any Navellier Investment Product.
Navellier claims compliance with Global Investment Performance Standards (GIPS). To receive a complete list and descriptions of Navellier’s composites and/or a presentation that adheres to the GIPS standards, please contact Navellier or click here. It should not be assumed that any securities recommendations made by Navellier & Associates, Inc. in the future will be profitable or equal the performance of securities made in this report.
FactSet Disclosure: Navellier does not independently calculate the statistical information included in the attached report. The calculation and the information are provided by FactSet, a company not related to Navellier. Although information contained in the report has been obtained from FactSet and is based on sources Navellier believes to be reliable, Navellier does not guarantee its accuracy, and it may be incomplete or condensed. The report and the related FactSet sourced information are provided on an “as is” basis. The user assumes the entire risk of any use made of this information. Investors should consider the report as only a single factor in making their investment decision. The report is for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of a security. FactSet sourced information is the exclusive property of FactSet. Without prior written permission of FactSet, this information may not be reproduced, disseminated or used to create any financial products. All indices are unmanaged and performance of the indices include reinvestment of dividends and interest income, unless otherwise noted, are not illustrative of any particular investment and an investment cannot be made in any index. Past performance is no guarantee of future results.