by Bryan Perry
September 15, 2026
A shift in the 10-year U.S. Treasury yield from the 4.0%-4.5% range up to 4.5%-5.0% triggered a knee-jerk negative reaction in financial markets. Traditional stock market theory says higher risk-free rates squeeze equity valuations by raising corporate borrowing costs and the discount rate on future cash flows.
However, equity markets do not trade on interest rates in a vacuum; they trade on the reasons why those rates are moving. When a yield increase is driven by robust economic expansion rather than stagflation, stocks not only tolerate higher yields but appreciate with them. The domestic macroeconomic backdrop demonstrates why equities are equipped to absorb a 4.5-5.0% 10-year Treasury rate and push higher.
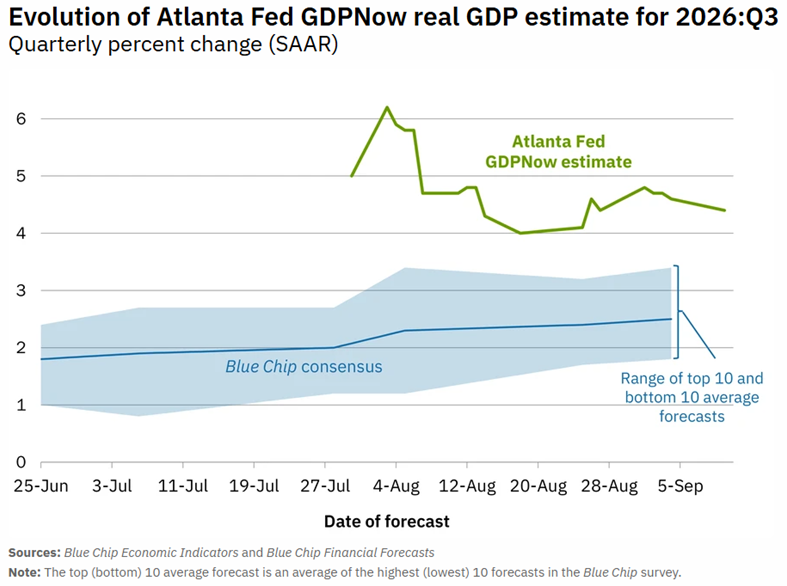
Interest rates rise for two primary reasons: (1) tightening monetary policy to combat inflation, or (2) expanding economic output. Current real U.S. Gross Domestic Product is running at a strong 4.4% pace for the third quarter, per the Atlanta Fed GDPNow reading released on September 10. When combined with a baseline inflation rate of around 2.5%, projected nominal GDP growth reaches nearly 7%.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
As long as nominal GDP growth (at, say, 7%) is greater than the 10-year Treasury yield, currently at about 5%, the stock market can remain constructively bullish. Corporate top-line revenue tracks nominal economic growth, not real (after inflation) GDP alone. If nominal economic output expands at nearly 7%, companies can generate sufficient revenue expansion to absorb a 4.5%–5.0% interest rate hurdle rate.
Historically, as long as top-line sales growth exceeds the risk-free rate, corporate profit margins remain durable. Whether this formula plays out now, as in past cycles, only time will tell, but it is important to note that prior to the 2008 Great Recession, 10-year Treasury yields were higher than modern investors are accustomed to seeing. Yields routinely averaged between roughly 5.0% and 5.5% from 1997 to 2006.
Equity markets did not just tolerate these higher rates back then – they experienced two of the strongest structural bull rallies in history. First, the Dot Com boom of 1995-1999 saw the 10-year yield trade in a range of 5.2% to 7.1% with the S&P 500 gaining 220%, or 25% annualized returns over that stretch. Then, in the 2003-2007 economic expansion, the 10-year yield traded rose from 3.3% to 5.2%, coming out of the dot com bust, reflecting broad global economic growth and corporate margin expansion.
The market narrative leading up to this week’s FOMC meeting is dominated by phenomenal earnings growth versus multiple contraction due to higher bond yields. While the 50-basis-point increase in 10-year yields recently witnessed can compress the S&P 500 forward P/E multiple slightly, say from 22x to 20x, robust economic activity delivers profit expansion that far outweighs this valuation haircut.
FactSet released their latest 3Q forecast on September 11. For Q3 2026, the estimated (year-over-year) earnings growth rate for the S&P 500 is 28.7%. If 28.7% is the actual growth rate for the quarter, it will mark the third-straight quarter of earnings growth above 25% for the index. All 11 S&P sectors are projected to report year-over-year growth. Five of these 11 sectors are predicted to report double-digit growth, led by the Energy, Information Technology, Communication Services, and Materials sectors.
On June 30, the estimated (year-over-year) earnings growth rate for the S&P 500 for Q3 2026 was 26.6%. For Q3 2026, 42 S&P 500 companies have issued negative EPS guidance, and 72 S&P 500 companies have issued positive EPS guidance. The forward 12-month P/E ratio for the S&P 500 is 19.1, below the 5-year average (19.8) but near the 10-year average (19.0). So far, the first two S&P 500 companies with Q3 results reported a positive EPS surprise, and both companies have reported a positive revenue surprise.
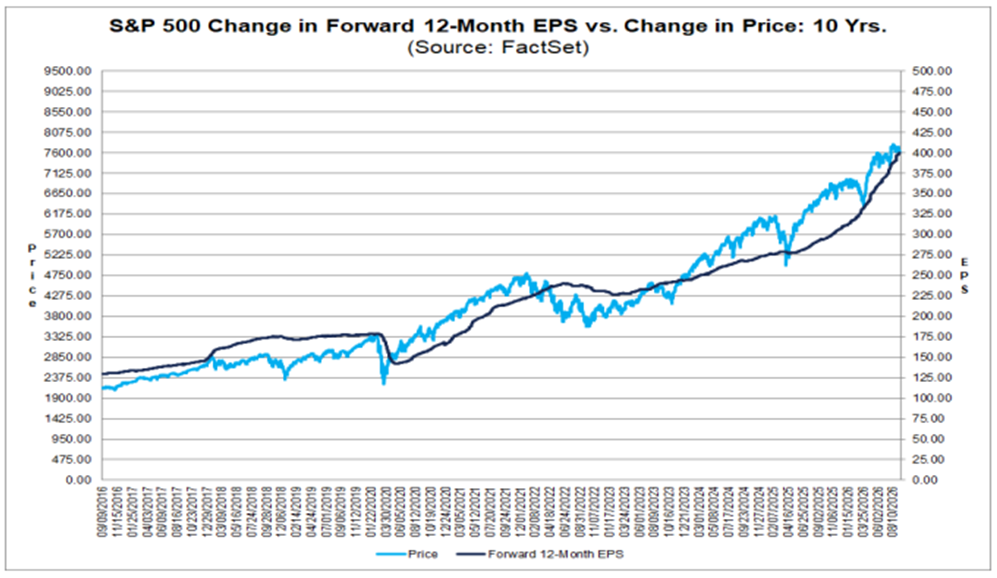
From the chart below, earnings for the S&P are trending notably higher. Coming into the quarter’s end in two-weeks, the market is not expensive on a historical basis.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
When S&P 500 earnings grow at double-digit rates, a mild contraction in P/E ratios results in a positive return for equities. Earnings are the key engine for stock prices, and a strong GDP ensures that corporate earnings remain on solid footing. S&P 500 companies also hold collective cash reserves exceeding $1.8 trillion. With short-term money market rates and 10-year Treasuries yielding near 5%, corporations are earning significant interest income on their cash holdings, effectively offsetting higher refinancing costs.
A primary bear case against higher yields is the burden of rising interest expense on corporate debt. However, U.S. large-cap corporations spent years refinancing debt at historically low fixed rates, and over 75% of S&P 500 corporate debt is structured into long-term, low-coupon, fixed-rate maturities.
Equity markets perform exceptionally well in a 4% to 5% yield regime because it reflects a healthy, non-recessionary economy, so high yields caused by economic vitality are usually a bull market catalyst.
Yes, there is some inflation evident in energy, food, travel and shelter, per the latest CPI report showing headline CPI up 0.4% month-over-month and 3.4% year-over-year. The core CPI (excluding food and energy) increased 0.3% over the month, with its annual pace easing slightly to 2.4%.
That said, a move in the 10-year Treasury yield to nearly 5.0% marks a return to historical norms. Driven by nominal inflation, forward-looking GDP growth of 4%+, double-digit corporate earnings growth, and AI-induced margin expansion, equities can absorb higher rates and appreciate to new record highs.
All content above represents the opinion of Bryan Perry of Navellier & Associates, Inc.
Also In This Issue
A Look Ahead by Louis Navellier
Inflation Returns, Raising the Odds for a Key Fed Rate Increase
Income Mail by Bryan Perry
Stocks Adjust to a “New Normal” for 10-Year Treasury Rates
Growth Mail by Gary Alexander
The Monthly “Confidence Index” Reveals Irrational Fears
Global Mail by Ivan Martchev
Here Comes the Fed Rate Hike
Sector Spotlight by Jason Bodner
Markets Have Shape…and Memory
View Full Archive
Read Past Issues Here
Important Disclosures:
Although information in these reports has been obtained from and is based upon sources that Navellier believes to be reliable, Navellier does not guarantee its accuracy and it may be incomplete or condensed. All opinions and estimates constitute the authors opinions as of the date the report was created and are subject to change without notice. These reports are for informational purposes only and are not a solicitation for the purchase or sale of any securities or financial services. Any decision to purchase securities mentioned in these reports must take into account existing public information on such securities or any registered prospectus. To the extent permitted by law, neither Navellier & Associates, Inc., nor any of its affiliates, agents, or service providers are providing any investment advice herein and do not assume any liability or responsibility for the readers’ decisions if any. No reader should act or refrain from acting in reliance on the information contained in this communication or for any decision based on it.
None of the stock information, data, or company information presented herein constitutes investment advice or a recommendation by Navellier or a solicitation to buy or sell any securities. Any specific securities identified and described herein do not represent any investment advice.
Information presented is general information that does not take into account your individual circumstances, financial situation, or needs, nor does it present a personalized recommendation to you. Individual stocks presented may not be suitable for every investor. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. Investment in fixed income securities has the potential for the investment return and principal value of an investment to fluctuate so that an investor’s holdings, when redeemed, may be worth less than their original cost.
- This report contains statements that are, or may be considered to be, forward-looking statements. All statements that are not historical facts, including statements about our beliefs or expectations, are “forward-looking statements” within the meaning of The U.S. Private Securities Litigation Reform Act of 1995. These statements may be identified by such forward-looking terminology as “expect,” “estimate,” “plan,” “intend,” “believe,” “anticipate,” “may,” “will,” “should,” “could,” “continue,” “project,” or similar statements or variations of such terms. Our forward-looking statements are based on a series of expectations, assumptions, and projections, are not investment advice. All of our forward-looking statements are as of the date of this report only.
- Federal Tax Advice Disclaimer: As required by U.S. Treasury Regulations, you are informed that, to the extent this presentation mentions any federal taxes, Navellier is not presenting any tax advice and should not be used or relied on as tax advice. Navellier does not advise on any income tax requirements or issues. Use of any information presented by Navellier is for general information only and does not represent tax advice either express or implied. You are encouraged to seek professional tax advice for income tax questions and assistance.
- FactSet Disclosure: Navellier does not independently calculate the statistical information included in the attached report. The calculation and the information are provided by FactSet, a company not related to Navellier. Although information contained in the report has been obtained from FactSet and is based on sources Navellier believes to be reliable, Navellier does not guarantee its accuracy, and it may be inaccurate, incomplete or condensed. The report and the related FactSet sourced information is for general information purposes only.