by Jason Bodner
September 15, 2026
Twenty-five years ago on September 11th, the world changed. For those who were there, and for those who lost someone, I take a moment to remember them. History lives through memory… never forget.
In 1962, U.S. Naval researchers discovered something remarkable. When a nickel-titanium alloy called Nitinol was bent out of shape and then heated, it snapped back to its original form.
This metal had memory.
You can see this with a paper clip. Bend it under pressure, apply heat, and it pops back to where it was.
This example of “shape memory” isn’t just a metaphor… Markets have the same property.
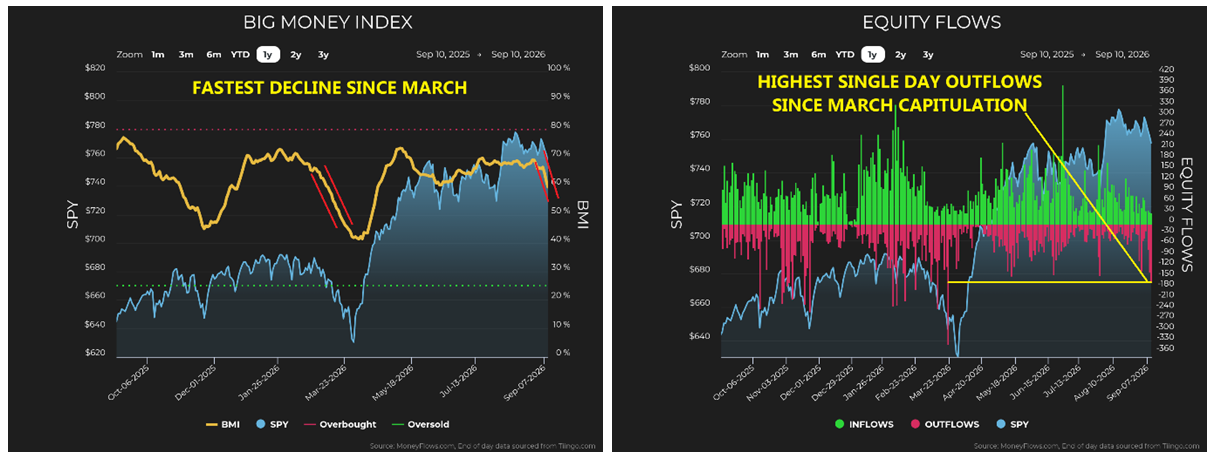
Specifically, our Big Money Index (BMI) fell 9.5 points from 69.2% on August 27 to 58.3% last Friday – the fastest decline since the March sell-off. Brent crude oil prices rose 21% in the same period, and last Wednesday saw 161 equity outflows, the highest single-day reading since the March 20 capitulation.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
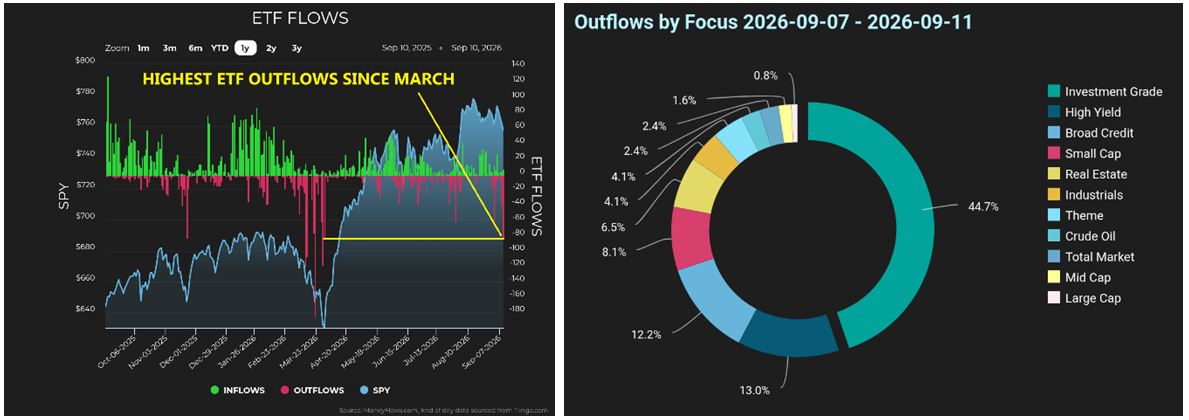
This selling is real, broadening, and intensifying. ETF flows confirm it, as 86 fixed income ETFs saw outflows in every maturity, every credit quality and every geography. Also, 34 equity ETFs were sold.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
The Wider Context the Data Provides
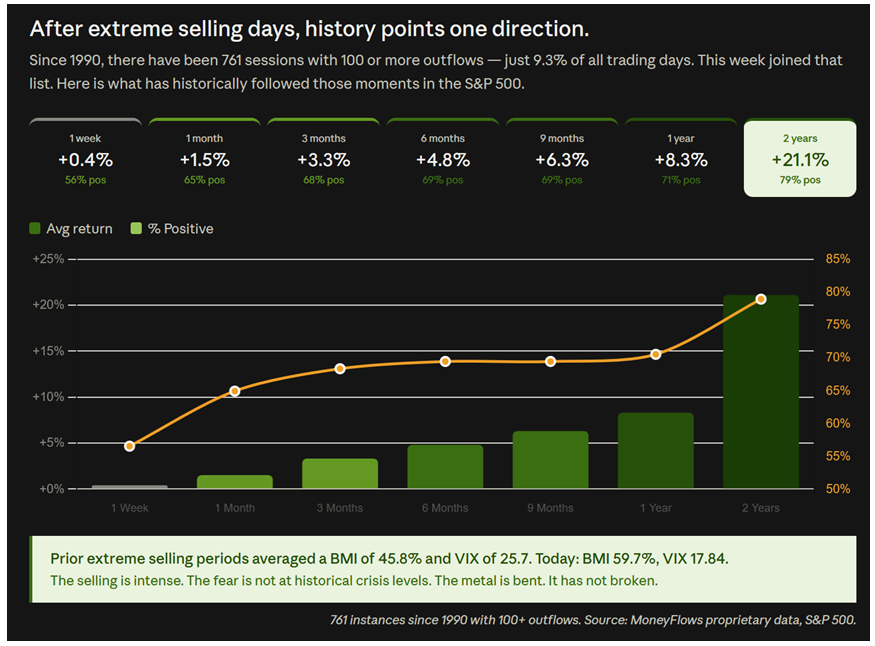
When things get bumpy, like I’ve just described, we tend to think crisis, but here is what makes this decline different. September 9th and 10th saw outflow counts exceed 100. The 36-year daily average is 37, so 100 is nearly triple. Since 1990, there were 761 sessions with 100 or more outflows including last week. Out of 9,214 trading sessions, that’s relatively rare – only about 9.3% of all days in 36 years.
But the future still looks bright: Look at the forward returns for such instances of 100 outflows or more:
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Prior averages saw a BMI of 45.8% and a VIX of 25.7. This week’s BMI sits at 58.3% and the VIX at 17.8. Selling may be intensifying but fear is not yet at historical crisis levels.
The metal is bent. It has not broken.
Oil drives everything now. The Strait of Hormuz handles one-fifth of global oil. Disrupt that flow and oil spikes, inflation rises, bond yields ramp and the Fed faces pressure even though the Fed can’t produce oil.
Seeing $100 crude or $107 Brent as midterm elections approach is economically and politically untenable. The recent Venezuelan deal securing a 35% equity stake in 65 billion barrels of reserves suggests preparations began before the escalation. The incentives for resolution are enormous.
The latest CPI shows why you need to look beneath the headline CPI number, which rose 0.4% in August. Strip out food and energy and the core CPI rose 0.3%. Unpack further, and hotels and airline fares rose. August was a heavy travel month. Medical care and car insurance costs fell. Inflation wasn’t everywhere.
Still, the CME FedWatch probability of a September rate hike tomorrow blasted up to roughly 90%.
That puts the Fed in a tough spot. Higher rates can squelch demand, but they won’t make more oil or reopen the Strait of Hormuz. They only add pressure to consumers getting killed at the pump.
When the oil shock fades, inflation fades with it. If it doesn’t, the Fed’s job gets harder. But don’t fear the big-bad rate hike yet. History says stocks do fine after hikes, as long as they are smooth and not fast:
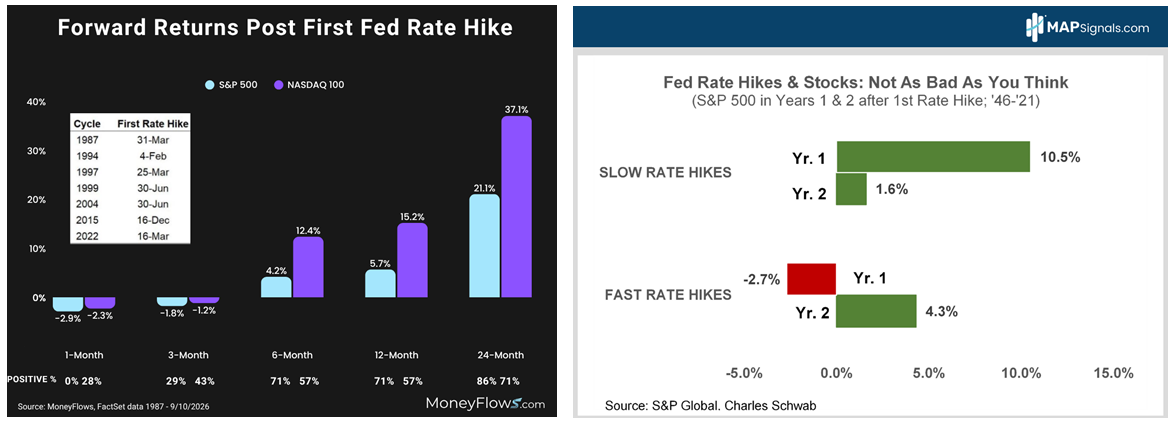
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
The Roadmap Has Mile Markers
Let’s see some useful data. Using daily NASDAQ returns since 1990, we can identify weak months, and also which weeks within those months carry the most historical weight. September’s third and fourth-weeks are historically the weakest of the month, averaging negative daily returns with less than 48% of days positive. We are entering that window now. In midterm election years, the pattern is even more pronounced, with the final week of September averaging losses in more than 90% of historical instances.
October’s first week is historically the worst of the entire month in midterm years, averaging a daily return of negative 0.49% with only 36% of days positive. That is typically the capitulation window. But October’s third week is the strongest of the month, averaging +0.62% a day with 62% of sessions higher.
Midterm Novembers have been consistently positive all four weeks. Week four of November averages positive returns with a 69% win rate — reflecting the initial rally, after the midterm result locks in.
December is modest by comparison. The heavy lifting happens in November.
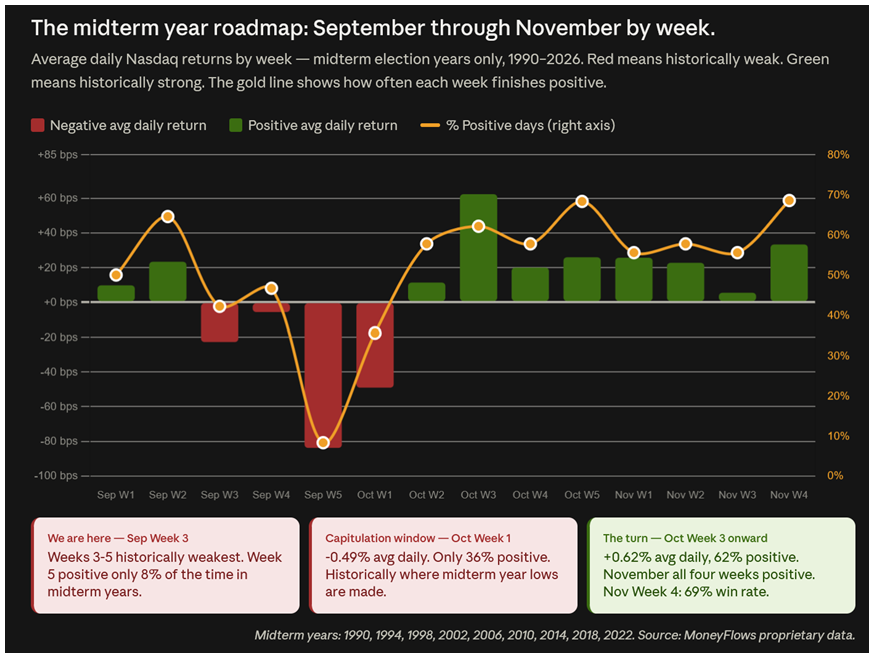
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
We expected bumpy. And it got bumpy. But the data say relief comes in October.
Sector Spotlight
Energy led all sectors inflows, as E&P producers saw direct bets on sustained oil prices. Healthcare, which had posted 11-consecutive weeks of inflows, saw net outflows as risk reduction swept through everything. Discretionary saw the largest outflows at minus 95, with consumer-facing names bearing the brunt of inflation and rate anxiety. Real estate followed at minus 52, and Industrials at minus 32.
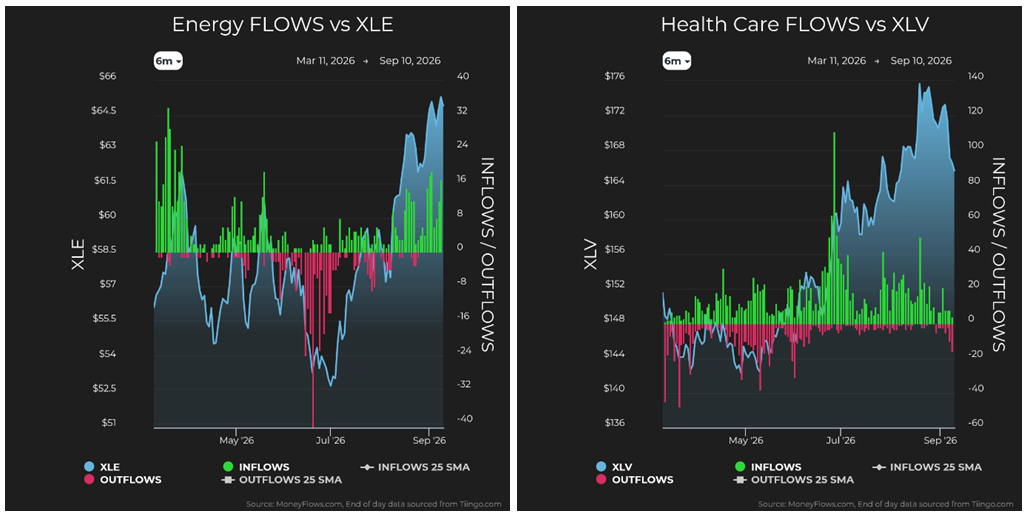
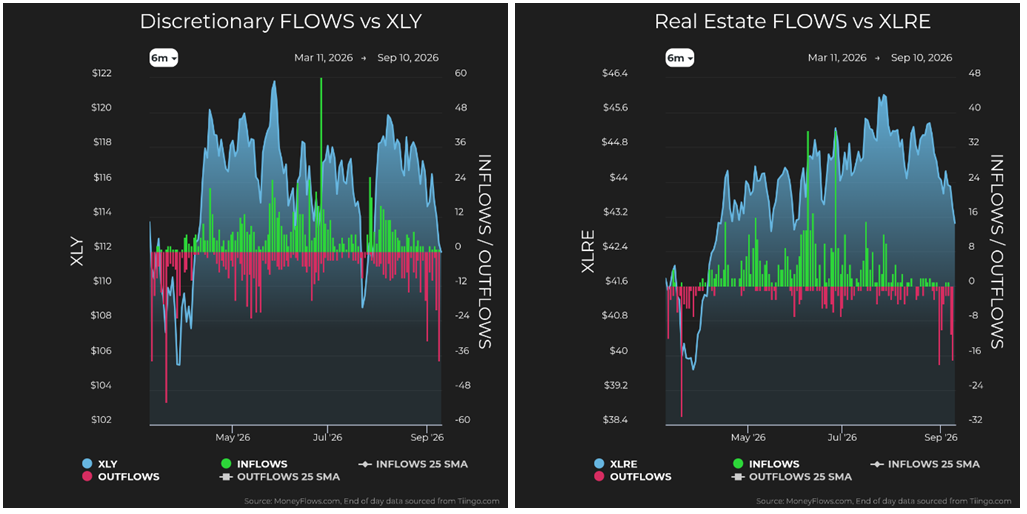
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
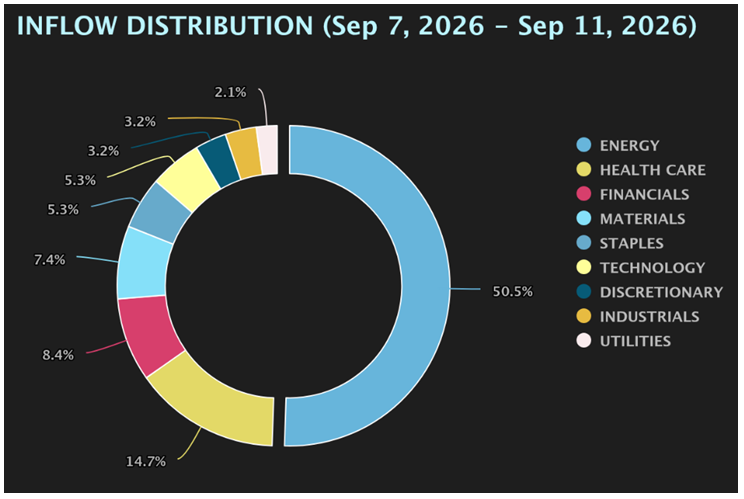
Energy captured 50.5% of all equity inflows last week, with one sector absorbing more than half of everything institutions were willing to buy. When half of all buying concentrates in a single sector, the market is not rotating. It is chasing return. Oil is the lever that explodes margins for energy producers.
The selling last week was not concentrated in one area. It was distributed across nearly every sector outside energy. That is the signature of macro-driven risk reduction, not sector rotation.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Nitinol doesn’t gradually ease back into shape. It snaps. The transition happens at a specific temperature. Below it, the metal holds the form pressure imposed. Above it, the original shape reasserts itself.
The trigger for today’s market would a Hormuz resolution. When it comes, the unwind won’t be gradual. Oil prices will fall. Inflation will recede. Bond yields will compress. Growth stocks will reprice.
As Seneca wrote, “Fire is the test of gold. Adversity, of strong men.”
September represents fire.
All content above represents the opinion of Jason Bodner of Navellier & Associates, Inc.
Also In This Issue
A Look Ahead by Louis Navellier
Inflation Returns, Raising the Odds for a Key Fed Rate Increase
Income Mail by Bryan Perry
Stocks Adjust to a “New Normal” for 10-Year Treasury Rates
Growth Mail by Gary Alexander
The Monthly “Confidence Index” Reveals Irrational Fears
Global Mail by Ivan Martchev
Here Comes the Fed Rate Hike
Sector Spotlight by Jason Bodner
Markets Have Shape…and Memory
View Full Archive
Read Past Issues Here
Important Disclosures:
Although information in these reports has been obtained from and is based upon sources that Navellier believes to be reliable, Navellier does not guarantee its accuracy and it may be incomplete or condensed. All opinions and estimates constitute the authors opinions as of the date the report was created and are subject to change without notice. These reports are for informational purposes only and are not a solicitation for the purchase or sale of any securities or financial services. Any decision to purchase securities mentioned in these reports must take into account existing public information on such securities or any registered prospectus. To the extent permitted by law, neither Navellier & Associates, Inc., nor any of its affiliates, agents, or service providers are providing any investment advice herein and do not assume any liability or responsibility for the readers’ decisions if any. No reader should act or refrain from acting in reliance on the information contained in this communication or for any decision based on it.
None of the stock information, data, or company information presented herein constitutes investment advice or a recommendation by Navellier or a solicitation to buy or sell any securities. Any specific securities identified and described herein do not represent any investment advice.
Information presented is general information that does not take into account your individual circumstances, financial situation, or needs, nor does it present a personalized recommendation to you. Individual stocks presented may not be suitable for every investor. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. Investment in fixed income securities has the potential for the investment return and principal value of an investment to fluctuate so that an investor’s holdings, when redeemed, may be worth less than their original cost.
- This report contains statements that are, or may be considered to be, forward-looking statements. All statements that are not historical facts, including statements about our beliefs or expectations, are “forward-looking statements” within the meaning of The U.S. Private Securities Litigation Reform Act of 1995. These statements may be identified by such forward-looking terminology as “expect,” “estimate,” “plan,” “intend,” “believe,” “anticipate,” “may,” “will,” “should,” “could,” “continue,” “project,” or similar statements or variations of such terms. Our forward-looking statements are based on a series of expectations, assumptions, and projections, are not investment advice. All of our forward-looking statements are as of the date of this report only.
- Federal Tax Advice Disclaimer: As required by U.S. Treasury Regulations, you are informed that, to the extent this presentation mentions any federal taxes, Navellier is not presenting any tax advice and should not be used or relied on as tax advice. Navellier does not advise on any income tax requirements or issues. Use of any information presented by Navellier is for general information only and does not represent tax advice either express or implied. You are encouraged to seek professional tax advice for income tax questions and assistance.
- FactSet Disclosure: Navellier does not independently calculate the statistical information included in the attached report. The calculation and the information are provided by FactSet, a company not related to Navellier. Although information contained in the report has been obtained from FactSet and is based on sources Navellier believes to be reliable, Navellier does not guarantee its accuracy, and it may be inaccurate, incomplete or condensed. The report and the related FactSet sourced information is for general information purposes only.
- Mapsignals Disclosure: Jason Bodner is a co-founder and co-owner of Mapsignals.com, a Developed Factor Model for isolating outlier stocks using its proprietary quantitative equity selection methodology. Mapsignals was founded in 2014. Data used by Mapsignals, for periods prior to its founding in 2014, is data derived from Factset. Mr. Bodner is an independent contractor who is occasionally hired to write articles and provide his editorial comments and opinions. Mr. Bodner is not employed by Navellier & Associates, Inc., or any other Navellier owned entity. The opinions and statements made in this article are those of Mr. Bodner and not necessarily those of any other persons or entities. Jason Bodner is a co-founder and co-owner of Mapsignals. Mr. Bodner is an independent contractor who is occasionally hired by Navellier & Associates to write an article and or provide opinions for possible use in articles that appear in Navellier & Associates weekly Market Mail. Mr. Bodner is not employed or affiliated with Louis Navellier, Navellier & Associates, Inc., or any other Navellier owned entity. The opinions and statements made here are those of Mr. Bodner and not necessarily those of any other persons or entities. This is not an endorsement, or solicitation or testimonial or investment advice regarding the BMI Index or any statements or recommendations or analysis in the article or the BMI Index or Mapsignals or its products or strategies.