by Jason Bodner
November 3, 2026
In February 1995, Newsweek ran a column by astronomer Clifford Stoll called, “Why the Web Won’t Be Nirvana.” He mocked the idea that people would ever shop online. Over 30-years later, the company that started selling books online just reported $202 billion in quarterly sales. Its stock fell anyway.
Doubting the future is popular in the mass media, but pessimism is usually not very profitable.
AI stocks took another gut-punch last week. Some companies collapsed as much as 27%. NASDAQ 100 futures were down about 2.5% before Friday’s open. Naturally, the headlines are saying: “The AI trade is dying!”
I’ve heard this song before. Over the summer, forced liquidations at Situational Awareness dragged AI stocks lower The narrative was there, but the death wasn’t.
Here’s what’s really happening: Investors are tired of paying for spending. Big firms are pouring so much into data-centers that free cash flow went negative. One plummeted 30% on Friday due to a shrinking PC business and weak guidance.
This isn’t a theme about technology dying… this is a bearish consolidation to prepare for the next leg higher.
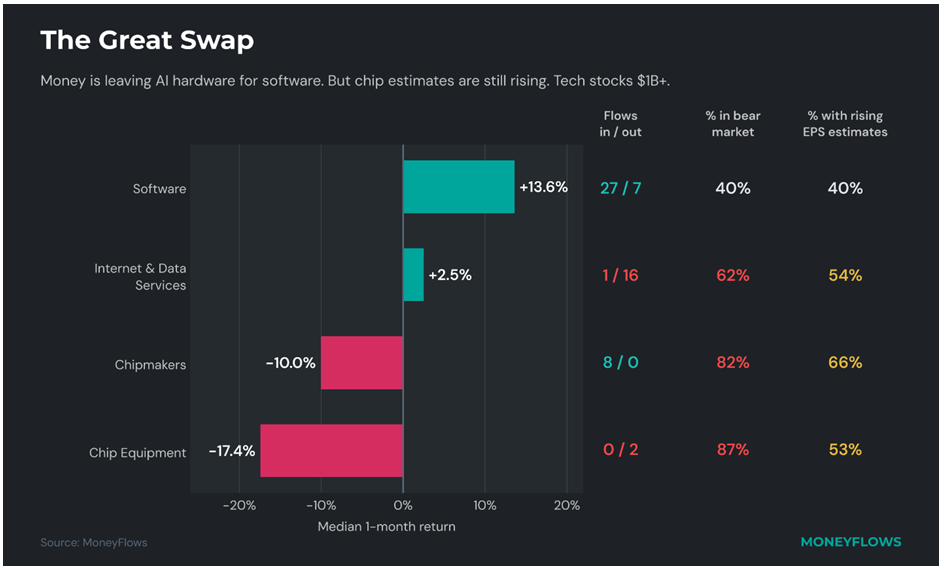
The money isn’t leaving technology… it’s swapping segments and sectors.
Example: Last week, software stocks showed 27 unusual inflows against just 7 outflows. Internet and data services saw one inflow against 16 outflows. Over the past month, the median software stock is up 13.6% while the median chip equipment stock is down 17.4%.
Remember the “SaaSpocalypse”? Software was supposedly finished. Now 15 of the 20 top-ranked stocks in our technology universe are software companies.
Here’s what almost no one is talking about. While chip stocks get crushed, analysts are raising their numbers. Among chipmakers worth $1 billion or more, 66% have seen quarterly earnings estimates rise over the past month. Only 16% have seen them fall. Yet 82% of those same stocks are in a bear market.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Prices are falling while earnings estimates are rising. That sounds like opportunity to me.
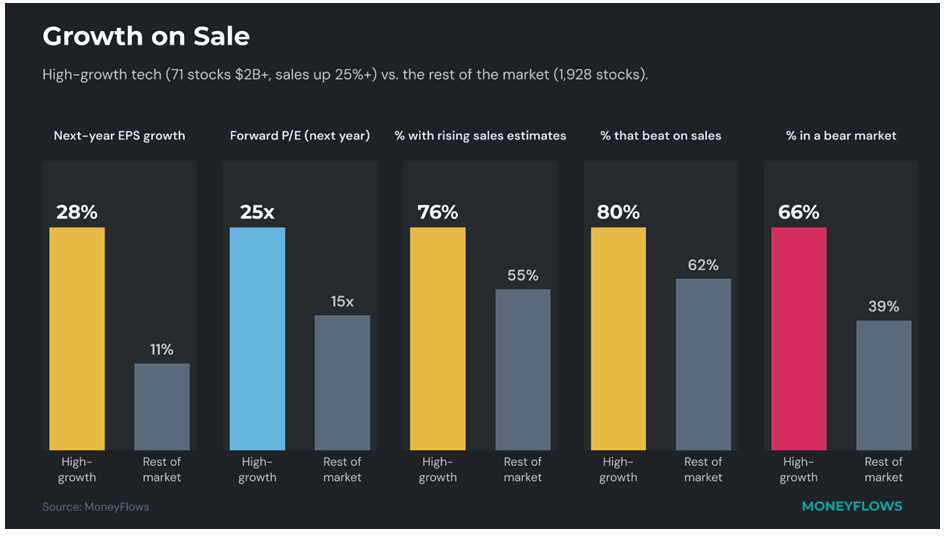
Looking at every technology stock worth $2 billion or more that’s growing sales 25% or faster, I find 71 in my data. Analysts expect their earnings to grow 28% next year vs. 11% for the rest of the market. They trade at 25-times forward earnings, so you pay less per point of growth than for the average stock. Three of four have rising sales estimates. Four of five beat on sales last quarter and two of three are down 20% or more.
Growth is on sale.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Outside technology, money is moving, not leaving. We logged 263 inflows against 188 outflows last week. Health care led with 63-buys, mostly big drugmakers and labs that serve them. Energy went 24-2 on oil above $100, and defense contractors led industrials for the same reason. Utilities had 17 buys and 0 sells.
The consumer is showing up, too, with buying in hotel REITs, apparel retailers, cruise lines, and restaurants. That fits GDP growing 3.4% last-quarter.
That’s not panic. That’s rotation. And rotation is what healthy markets do before the next advance.
Which brings me to the calendar. The midterms are Tuesday, and history is screaming bullish.
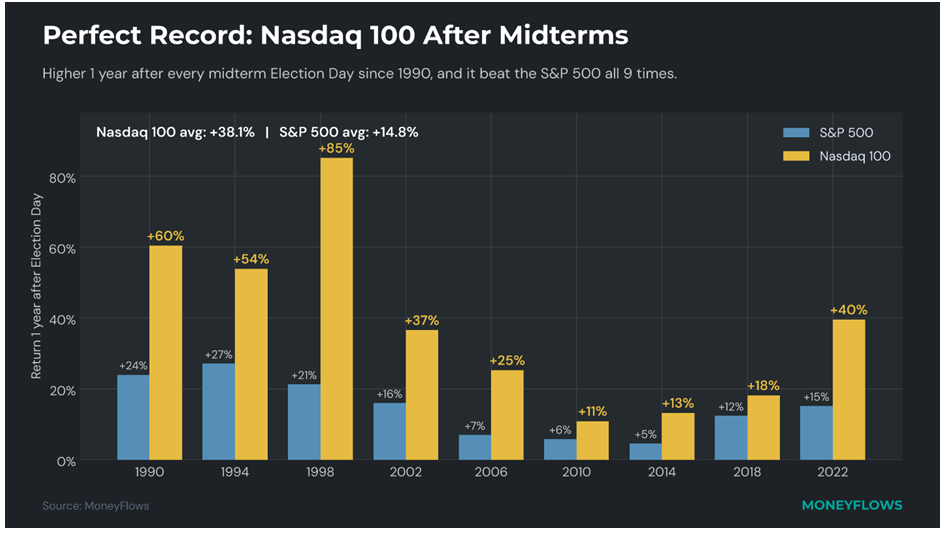
Since 1950, the S&P 500 has been higher 12-months after all 19 midterm elections, with an average gain of about 15%. Technology does even better. Since 1990, the NASDAQ 100 has been higher one-year after every midterm Election Day. That’s 9 for 9, with an average gain of 38.1%, and it beat the S&P 500 all 9-times.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
The seasonal tailwinds stack up too. The fourth-quarter of a midterm year has been positive 16 of 19-times since 1950, averaging 6.6%. And 2027 is the third year of the presidential term, the pre-election year. Since 1950, the S&P 500 has fallen in only two of them, 2011 and 2015, both by less than 1%. In our data, the NASDAQ 100 rose in all nine pre-election years since 1991, by an average of 42.2%.
It gets better. In midterm years with real turmoil before the election, the NASDAQ 100 averaged a 47.9% gain the following year. In calmer years, it averaged 25.8%. This year the index looks calm, but the median chipmaker is 34% off its high. The tumult is real. It’s just hiding behind the index.
Then there’s the Big Money Index (BMI). It bottomed out at 22.9% on October 14, then climbed to 35.3%. Since 1990, the BMI has exited oversold during a midterm year 12-times. The S&P 500 was higher one-year later every time, with an average gain of 14.4%. Two-years later, it was up 30.2% on average.
That’s three perfect records, all pointing in the same direction.
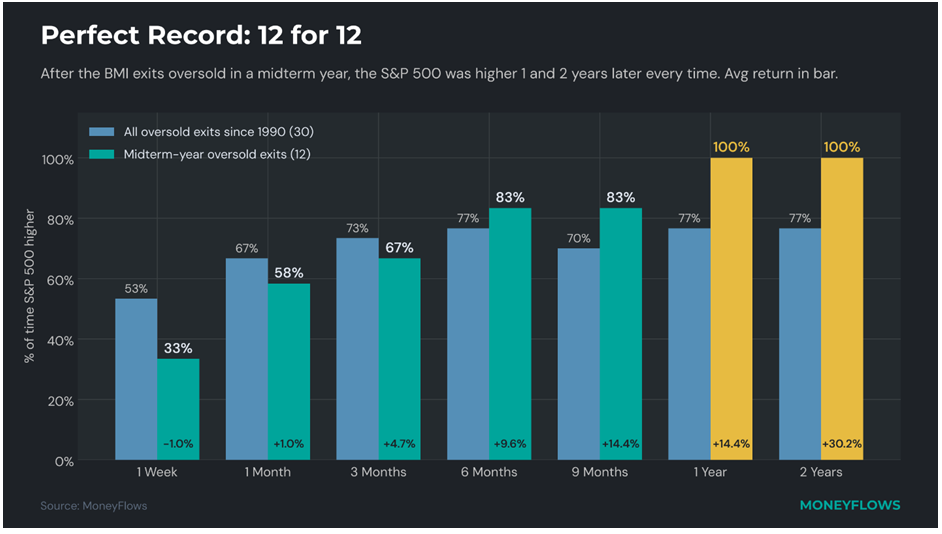
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
So where do the opportunities rise in 2027? I screened for stocks worth $2 billion or more in market cap-down at least 25% and also rank in the top quarter for fundamentals, with rising earnings estimates. That netted 73-stocks. Within those 73, over one-third (35.6%) were AI buildout companies: chips, storage, power equipment, and data-center builders. That’s not chance. That’s where the value is hiding.
The stocks being sold hardest have the best fundamentals and rising estimates. Add software already leading, health care and energy drawing steady money, and a consumer that keeps spending, and 2027 is setting up as a broad advance, not a narrow one.
Will it be smooth? Unlikely. One week after those BMI signals, stocks were higher only a third of the time. With interest rates above 5%, oil above $100, and an election this week, expect choppy markets. But chop after a bottom is normal. It’s how markets shake out the doubters before the next run.
My belief in these themes hasn’t wavered. Only the mood has. And moods, unlike data, don’t last.
As Seneca put it, “We suffer more often in imagination than in reality.”
All content above represents the opinion of Jason Bodner of Navellier & Associates, Inc.
Also In This Issue
A Look Ahead by Louis Navellier
Expect a Fractured G-20 Meeting in Florida Next Month
Income Mail by Bryan Perry
Using Energy Options to Take “Implied Market Volatility” to the Bank
Growth Mail by Gary Alexander
Today May Be the Best Day to Invest in the Post-Election Surge
Global Mail by Ivan Martchev
A Stock Market Bottom is Likely Within Reach
Sector Spotlight by Jason Bodner
Doubting the Future is Popular – But Not Very Profitable
Important Disclosures:
Jason Bodner is a co-founder and co-owner of Mapsignals. Mr. Bodner is an independent contractor who is occasionally hired by Navellier & Associates to write an article and or provide opinions for possible use in articles that appear in Navellier & Associates weekly Market Mail. Mr. Bodner is not employed or affiliated with Louis Navellier, Navellier & Associates, Inc., or any other Navellier owned entity. The opinions and statements made here are those of Mr. Bodner and not necessarily those of any other persons or entities. This is not an endorsement, or solicitation or testimonial or investment advice regarding the BMI Index or any statements or recommendations or analysis in the article or the BMI Index or Mapsignals or its products or strategies.
Although information in these reports has been obtained from and is based upon sources that Navellier believes to be reliable, Navellier does not guarantee its accuracy and it may be incomplete or condensed. All opinions and estimates constitute Navellier’s judgment as of the date the report was created and are subject to change without notice. These reports are for informational purposes only and are not a solicitation for the purchase or sale of a security. Any decision to purchase securities mentioned in these reports must take into account existing public information on such securities or any registered prospectus.To the extent permitted by law, neither Navellier & Associates, Inc., nor any of its affiliates, agents, or service providers assumes any liability or responsibility nor owes any duty of care for any consequences of any person acting or refraining to act in reliance on the information contained in this communication or for any decision based on it.
Past performance is no indication of future results. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. It should not be assumed that any securities recommendations made by Navellier. in the future will be profitable or equal the performance of securities made in this report. Dividend payments are not guaranteed. The amount of a dividend payment, if any, can vary over time and issuers may reduce dividends paid on securities in the event of a recession or adverse event affecting a specific industry or issuer.
None of the stock information, data, and company information presented herein constitutes a recommendation by Navellier or a solicitation to buy or sell any securities. Any specific securities identified and described do not represent all of the securities purchased, sold, or recommended for advisory clients. The holdings identified do not represent all of the securities purchased, sold, or recommended for advisory clients and the reader should not assume that investments in the securities identified and discussed were or will be profitable.
Information presented is general information that does not take into account your individual circumstances, financial situation, or needs, nor does it present a personalized recommendation to you. Individual stocks presented may not be suitable for every investor. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. Investment in fixed income securities has the potential for the investment return and principal value of an investment to fluctuate so that an investor’s holdings, when redeemed, may be worth less than their original cost.
One cannot invest directly in an index. Index is unmanaged and index performance does not reflect deduction of fees, expenses, or taxes. Presentation of Index data does not reflect a belief by Navellier that any stock index constitutes an investment alternative to any Navellier equity strategy or is necessarily comparable to such strategies. Among the most important differences between the Indices and Navellier strategies are that the Navellier equity strategies may (1) incur material management fees, (2) concentrate its investments in relatively few stocks, industries, or sectors, (3) have significantly greater trading activity and related costs, and (4) be significantly more or less volatile than the Indices.
ETF Risk: We may invest in exchange traded funds (“ETFs”) and some of our investment strategies are generally fully invested in ETFs. Like traditional mutual funds, ETFs charge asset-based fees, but they generally do not charge initial sales charges or redemption fees and investors typically pay only customary brokerage fees to buy and sell ETF shares. The fees and costs charged by ETFs held in client accounts will not be deducted from the compensation the client pays Navellier. ETF prices can fluctuate up or down, and a client account could lose money investing in an ETF if the prices of the securities owned by the ETF go down. ETFs are subject to additional risks:
- ETF shares may trade above or below their net asset value;
- An active trading market for an ETF’s shares may not develop or be maintained;
- The value of an ETF may be more volatile than the underlying portfolio of securities the ETF is designed to track;
- The cost of owning shares of the ETF may exceed those a client would incur by directly investing in the underlying securities and;
- Trading of an ETF’s shares may be halted if the listing exchange’s officials deem it appropriate, the shares are delisted from the exchange, or the activation of market-wide “circuit breakers” (which are tied to large decreases in stock prices) halts stock trading generally.
Grader Disclosures: Investment in equity strategies involves substantial risk and has the potential for partial or complete loss of funds invested. The sample portfolio and any accompanying charts are for informational purposes only and are not to be construed as a solicitation to buy or sell any financial instrument and should not be relied upon as the sole factor in an investment making decision. As a matter of normal and important disclosures to you, as a potential investor, please consider the following: The performance presented is not based on any actual securities trading, portfolio, or accounts, and the reported performance of the A, B, C, D, and F portfolios (collectively the “model portfolios”) should be considered mere “paper” or pro forma performance results based on Navellier’s research.
Investors evaluating any of Navellier & Associates, Inc.’s, (or its affiliates’) Investment Products must not use any information presented here, including the performance figures of the model portfolios, in their evaluation of any Navellier Investment Products. Navellier Investment Products include the firm’s mutual funds and managed accounts. The model portfolios, charts, and other information presented do not represent actual funded trades and are not actual funded portfolios. There are material differences between Navellier Investment Products’ portfolios and the model portfolios, research, and performance figures presented here. The model portfolios and the research results (1) may contain stocks or ETFs that are illiquid and difficult to trade; (2) may contain stock or ETF holdings materially different from actual funded Navellier Investment Product portfolios; (3) include the reinvestment of all dividends and other earnings, estimated trading costs, commissions, or management fees; and, (4) may not reflect prices obtained in an actual funded Navellier Investment Product portfolio. For these and other reasons, the reported performances of model portfolios do not reflect the performance results of Navellier’s actually funded and traded Investment Products. In most cases, Navellier’s Investment Products have materially lower performance results than the performances of the model portfolios presented.
This report contains statements that are, or may be considered to be, forward-looking statements. All statements that are not historical facts, including statements about our beliefs or expectations, are “forward-looking statements” within the meaning of The U.S. Private Securities Litigation Reform Act of 1995. These statements may be identified by such forward-looking terminology as “expect,” “estimate,” “plan,” “intend,” “believe,” “anticipate,” “may,” “will,” “should,” “could,” “continue,” “project,” or similar statements or variations of such terms. Our forward-looking statements are based on a series of expectations, assumptions, and projections, are not guarantees of future results or performance, and involve substantial risks and uncertainty as described in Form ADV Part 2A of our filing with the Securities and Exchange Commission (SEC), which is available at www.adviserinfo.sec.gov or by requesting a copy by emailing info@navellier.com. All of our forward-looking statements are as of the date of this report only. We can give no assurance that such expectations or forward-looking statements will prove to be correct. Actual results may differ materially. You are urged to carefully consider all such factors.
FEDERAL TAX ADVICE DISCLAIMER: As required by U.S. Treasury Regulations, you are informed that, to the extent this presentation includes any federal tax advice, the presentation is not written by Navellier to be used, and cannot be used, for the purpose of avoiding federal tax penalties. Navellier does not advise on any income tax requirements or issues. Use of any information presented by Navellier is for general information only and does not represent tax advice either express or implied. You are encouraged to seek professional tax advice for income tax questions and assistance.
IMPORTANT NEWSLETTER DISCLOSURE:The hypothetical performance results for investment newsletters that are authored or edited by Louis Navellier, including Louis Navellier’s Growth Investor, Louis Navellier’s Breakthrough Stocks, Louis Navellier’s Accelerated Profits, and Louis Navellier’s Platinum Club, are not based on any actual securities trading, portfolio, or accounts, and the newsletters’ reported hypothetical performances should be considered mere “paper” or proforma hypothetical performance results and are not actual performance of real world trades. Navellier & Associates, Inc. does not have any relation to or affiliation with the owner of these newsletters. There are material differences between Navellier Investment Products’ portfolios and the InvestorPlace Media, LLC newsletter portfolios authored by Louis Navellier. The InvestorPlace Media, LLC newsletters contain hypothetical performance that do not include transaction costs, advisory fees, or other fees a client might incur if actual investments and trades were being made by an investor. As a result, newsletter performance should not be used to evaluate Navellier Investment services which are separate and different from the newsletters. The owner of the newsletters is InvestorPlace Media, LLC and any questions concerning the newsletters, including any newsletter advertising or hypothetical Newsletter performance claims, (which are calculated solely by Investor Place Media and not Navellier) should be referred to InvestorPlace Media, LLC at (800) 718-8289.
Please note that Navellier & Associates and the Navellier Private Client Group are managed completely independent of the newsletters owned and published by InvestorPlace Media, LLC and written and edited by Louis Navellier, and investment performance of the newsletters should in no way be considered indicative of potential future investment performance for any Navellier & Associates separately managed account portfolio. Potential investors should consult with their financial advisor before investing in any Navellier Investment Product.
Navellier claims compliance with Global Investment Performance Standards (GIPS). To receive a complete list and descriptions of Navellier’s composites and/or a presentation that adheres to the GIPS standards, please contact Navellier or click here. It should not be assumed that any securities recommendations made by Navellier & Associates, Inc. in the future will be profitable or equal the performance of securities made in this report.
FactSet Disclosure: Navellier does not independently calculate the statistical information included in the attached report. The calculation and the information are provided by FactSet, a company not related to Navellier. Although information contained in the report has been obtained from FactSet and is based on sources Navellier believes to be reliable, Navellier does not guarantee its accuracy, and it may be incomplete or condensed. The report and the related FactSet sourced information are provided on an “as is” basis. The user assumes the entire risk of any use made of this information. Investors should consider the report as only a single factor in making their investment decision. The report is for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of a security. FactSet sourced information is the exclusive property of FactSet. Without prior written permission of FactSet, this information may not be reproduced, disseminated or used to create any financial products. All indices are unmanaged and performance of the indices include reinvestment of dividends and interest income, unless otherwise noted, are not illustrative of any particular investment and an investment cannot be made in any index. Past performance is no guarantee of future results.