by Jason Bodner
October 20, 2026
Each fall in Alaska, the wood frog lets itself freeze. Up to 60% of its body turns to ice and its heart stops. It’s pretty much dead, and it can stay “dead” for seven months. But to train for this near-death experience, the frog first goes through 10 to 15 freeze-and-thaw cycles to build up glucose that works like antifreeze.
Then, come spring, this wood frog’s heart starts beating again, after seven months in a deep freeze.
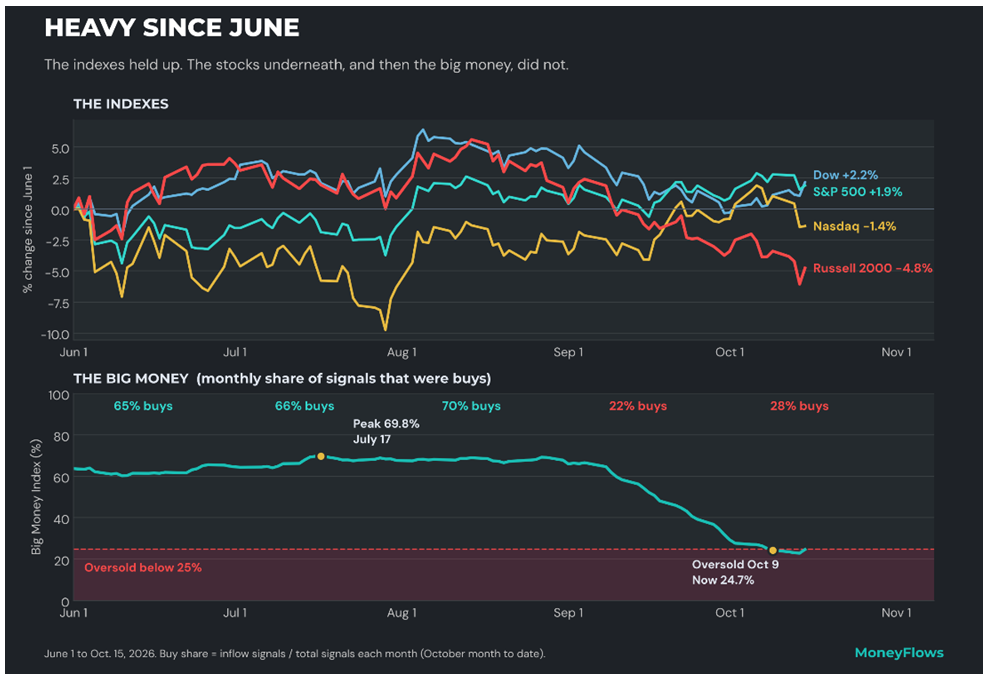
The market has been playing “frozen frog” for last few months (the southern hemisphere winter, which we call summer). Since June 1, the S&P 500 is up just 2% and remains just 1% off its October 6 record.
Underneath, however, the bulk of small stocks have been frozen. The Russell 2000 is down 4.8% since June 1. Of the roughly 5,300 stocks we track, 56% haven’t made a new 52-week high since July 1. More than half (51%) are down by 20% or more, the definition of a bear market in a stock or a market index.
Even the leaders cracked. Big chip and AI hardware names peaked in late June and have since fallen 23% to 42%. Fully 90% of chip equipment stocks are in a bear market, even though the group is up this year.
Money flows add a twist. Big money kept buying all summer. In June, July and August, inflows made up 65% to 70% of our unusual-activity signals. Then September hit. In September, big money pulled on the handbrake. Inflows fell to just 22% of signals, the worst month of the year, worse even than March.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Two things are controlling that handbrake. The first is rates. Wednesday’s CPI report came in hot. Thursday’s producer prices rose 6.3% from a year ago. The 10-year Treasury yield hit about 5.19% before easing to 5.085%. Traders now see a Fed rate hike in two weeks as close to a coin flip.
Higher rates squeeze borrowers. FINRA margin debt hit a record $1.50 trillion in June, then fell $84.8 billion in July, the biggest monthly dollar drop on record, as hedge fund Situational Awareness faced margin calls. August bounced 2.6% to $1.45 trillion. Borrowed money sells early to avoid margin calls.
Among stocks with over $2 billion in market cap, the most indebted fifth fell a median 2.9% last month while the least indebted rose 0.5%. Companies expected to post negative adjusted earnings (EBITDA) fell 12.3%. On Wednesday, high-yield, preferred and convertible bond ETFs were dumped.
Thursday showed what deleveraging looks like. AI hardware and memory stocks slid while the Dow rose 1.1% and the Russell 2000 jumped 1.4%. This year’s worst stocks rose a median 2.8%. The year’s best stocks were flat. The most shorted stocks gained 2.3%. Funds were selling their winners to cut risk, and short sellers were covering their losses.
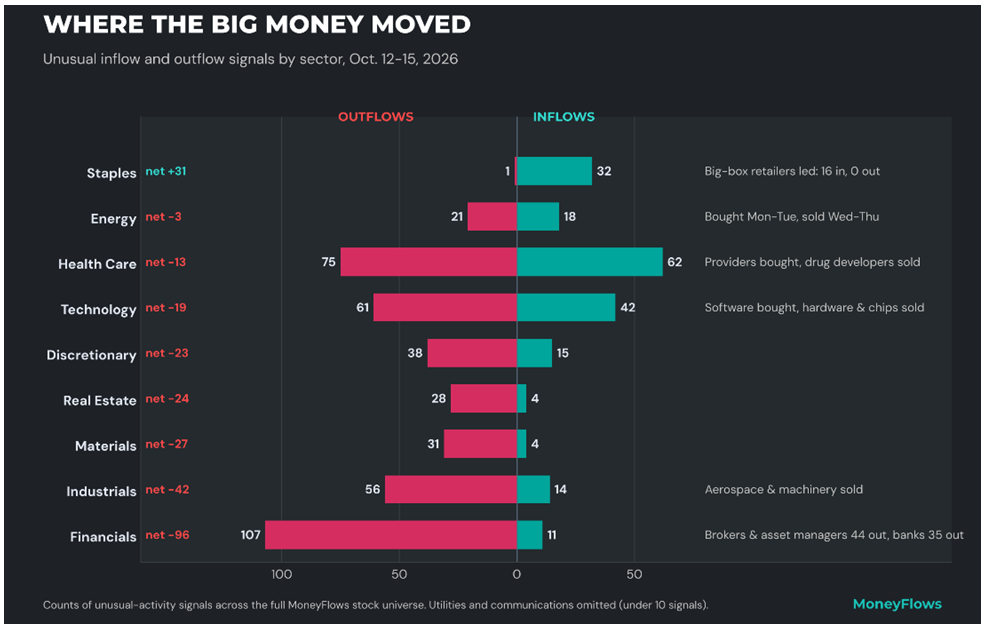
Sectors fill in the rest. From October 12 to 15, consumer staples were the biggest net buy, with 32 inflows and one outflow, led by big-box retailers. Health care split down the middle. Providers and services drew 19 inflows and no outflows, while drug developers took 47 outflows. Financials took the worst of it, 107 outflows against 11 inflows, as brokers, asset managers and banks sold off on mixed bank earnings.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
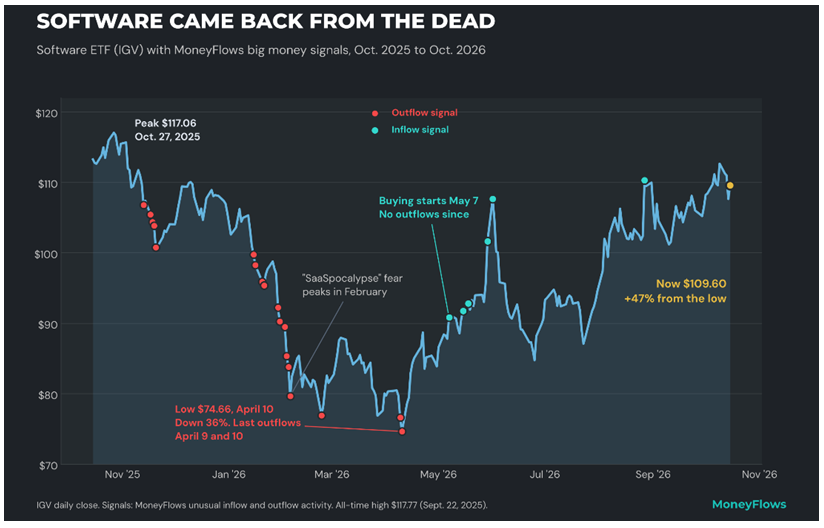
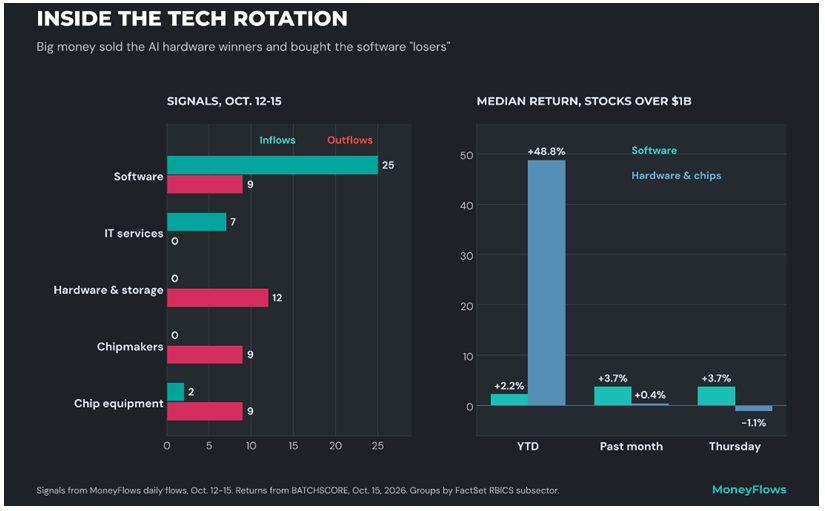
Technology made the most interesting move. Last winter, the fear was AI would replace software, the “software apocalypse.” IGV, the software ETF, fell 36%, with big money selling all the way down. The last outflow signals came on April 9 and 10, the final two-days of the drop. Then the buying started. Today IGV is up 47% from that low and sits within 7% of its all-time high. Last week, big money kept buying. Software drew 25 inflows and 9 outflows, while hardware and chip stocks took 33 outflows against 3 inflows.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
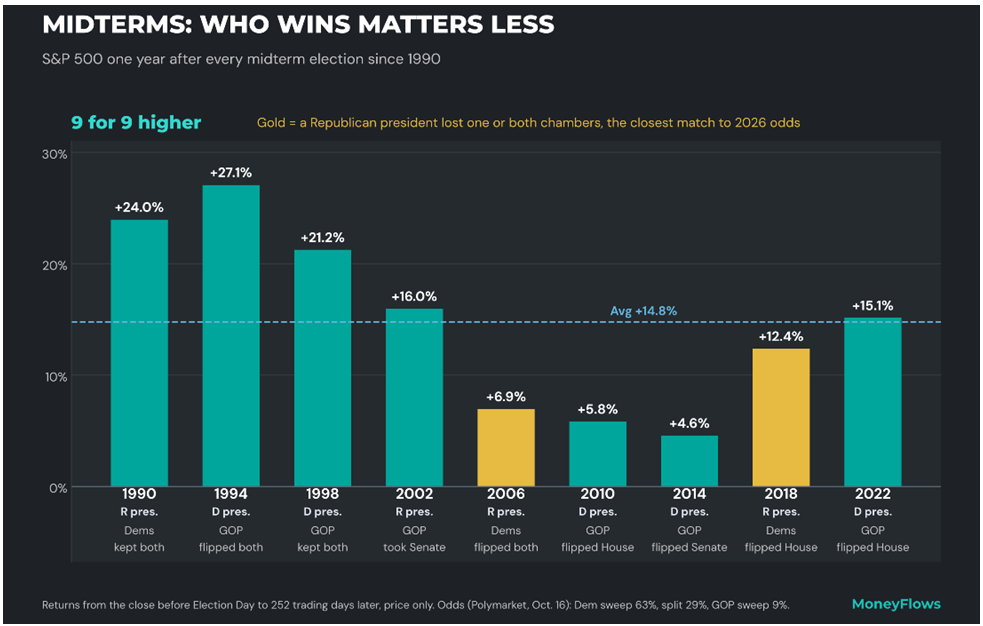
The second force holding the handbrake is the midterm election, coming soon, on November 3. Prediction markets give the Democrats a 63% chance of sweeping both chambers of Congress, with chances of a Republican Senate and Democratic House much lower, 29%. A Republican sweep has an 8%-9% chance.
History says getting the election behind us matters more than who wins. I looked at every midterm result since 1990. The S&P 500 was higher six months, nine months and one year later every time, in nine cycles. The average one-year gain was +14.8%. That includes 2006, when Democrats took both chambers from a Republican president (up 6.9%), and 2018, when Democrats took the House (+12.4%).
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
The War in Iran is another “brake” on the market. President Trump has said he expects a deal with Iran after the midterms. With Brent crude near $106, November 3 could lift two weights at once.
Now for the thaw… evident in three concurrent signals:
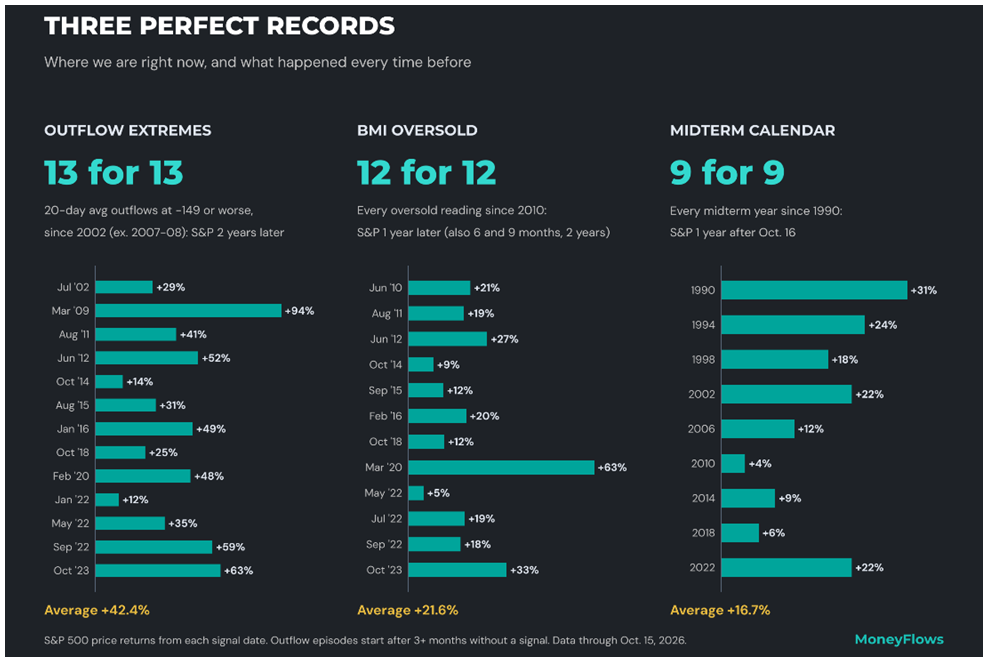
- On October 9, the Big Money Index (BMI) fell below 25% and went oversold. This is one of our strongest signals. Since 2010, the S&P 500 was higher six months, nine months, one year and two years after all 12 previous oversold readings. The average one-year gain was +21.6%.
- Outflows have been extreme, too. The 20-day average of daily outflows hit -149. Since 2002, leaving out the 2008 financial crisis, the S&P was higher two years later all 13 times, with an average gain of 42.4%.
- The calendar agrees. In seven of the last nine midterm years, the fall low came between October 2 and October 15. One year after October 16, the S&P was higher in all nine midterm years, with an average gain of 16.7%.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Thursday may have been the first heartbeat of the thawing process. Big money logged 99 inflows, the most since August 21. Inflows were 61% of signals, the first time above 50% since September 4. The BMI ticked higher for the first time in weeks, but it still remains under 25, at 24.7.
Like our frozen frog, the market had to go through its sleep cycles first. The summer fade, the September flush and this week’s deleveraging look like damage, but they’re also like antifreeze. The time for a major rally is close. We sweated through the summer. Now we are shivering… but the thaw is coming.
“Winter brings on cold weather; and we must shiver. Summer returns, with its heat; and we must sweat.”
–Seneca
All content above represents the opinion of Jason Bodner of Navellier & Associates, Inc.
Also In This Issue
A Look Ahead by Louis Navellier
Earnings Highlights from Week #1 of Third-Quarter Results
Income Mail by Bryan Perry
It’s “Show Time” for The AI Trade
Growth Mail by Gary Alexander
Anatomy of a Scary (but Meaningless) Market Collapse 39-Years Ago Today
Global Mail by Ivan Martchev
When Junk Bonds Get Junkier
Sector Spotlight by Jason Bodner
This Market is Frozen, Not Dead
Important Disclosures:
Jason Bodner is a co-founder and co-owner of Mapsignals. Mr. Bodner is an independent contractor who is occasionally hired by Navellier & Associates to write an article and or provide opinions for possible use in articles that appear in Navellier & Associates weekly Market Mail. Mr. Bodner is not employed or affiliated with Louis Navellier, Navellier & Associates, Inc., or any other Navellier owned entity. The opinions and statements made here are those of Mr. Bodner and not necessarily those of any other persons or entities. This is not an endorsement, or solicitation or testimonial or investment advice regarding the BMI Index or any statements or recommendations or analysis in the article or the BMI Index or Mapsignals or its products or strategies.
Although information in these reports has been obtained from and is based upon sources that Navellier believes to be reliable, Navellier does not guarantee its accuracy and it may be incomplete or condensed. All opinions and estimates constitute Navellier’s judgment as of the date the report was created and are subject to change without notice. These reports are for informational purposes only and are not a solicitation for the purchase or sale of a security. Any decision to purchase securities mentioned in these reports must take into account existing public information on such securities or any registered prospectus.To the extent permitted by law, neither Navellier & Associates, Inc., nor any of its affiliates, agents, or service providers assumes any liability or responsibility nor owes any duty of care for any consequences of any person acting or refraining to act in reliance on the information contained in this communication or for any decision based on it.
Past performance is no indication of future results. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. It should not be assumed that any securities recommendations made by Navellier. in the future will be profitable or equal the performance of securities made in this report. Dividend payments are not guaranteed. The amount of a dividend payment, if any, can vary over time and issuers may reduce dividends paid on securities in the event of a recession or adverse event affecting a specific industry or issuer.
None of the stock information, data, and company information presented herein constitutes a recommendation by Navellier or a solicitation to buy or sell any securities. Any specific securities identified and described do not represent all of the securities purchased, sold, or recommended for advisory clients. The holdings identified do not represent all of the securities purchased, sold, or recommended for advisory clients and the reader should not assume that investments in the securities identified and discussed were or will be profitable.
Information presented is general information that does not take into account your individual circumstances, financial situation, or needs, nor does it present a personalized recommendation to you. Individual stocks presented may not be suitable for every investor. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. Investment in fixed income securities has the potential for the investment return and principal value of an investment to fluctuate so that an investor’s holdings, when redeemed, may be worth less than their original cost.
One cannot invest directly in an index. Index is unmanaged and index performance does not reflect deduction of fees, expenses, or taxes. Presentation of Index data does not reflect a belief by Navellier that any stock index constitutes an investment alternative to any Navellier equity strategy or is necessarily comparable to such strategies. Among the most important differences between the Indices and Navellier strategies are that the Navellier equity strategies may (1) incur material management fees, (2) concentrate its investments in relatively few stocks, industries, or sectors, (3) have significantly greater trading activity and related costs, and (4) be significantly more or less volatile than the Indices.
ETF Risk: We may invest in exchange traded funds (“ETFs”) and some of our investment strategies are generally fully invested in ETFs. Like traditional mutual funds, ETFs charge asset-based fees, but they generally do not charge initial sales charges or redemption fees and investors typically pay only customary brokerage fees to buy and sell ETF shares. The fees and costs charged by ETFs held in client accounts will not be deducted from the compensation the client pays Navellier. ETF prices can fluctuate up or down, and a client account could lose money investing in an ETF if the prices of the securities owned by the ETF go down. ETFs are subject to additional risks:
- ETF shares may trade above or below their net asset value;
- An active trading market for an ETF’s shares may not develop or be maintained;
- The value of an ETF may be more volatile than the underlying portfolio of securities the ETF is designed to track;
- The cost of owning shares of the ETF may exceed those a client would incur by directly investing in the underlying securities and;
- Trading of an ETF’s shares may be halted if the listing exchange’s officials deem it appropriate, the shares are delisted from the exchange, or the activation of market-wide “circuit breakers” (which are tied to large decreases in stock prices) halts stock trading generally.
Grader Disclosures: Investment in equity strategies involves substantial risk and has the potential for partial or complete loss of funds invested. The sample portfolio and any accompanying charts are for informational purposes only and are not to be construed as a solicitation to buy or sell any financial instrument and should not be relied upon as the sole factor in an investment making decision. As a matter of normal and important disclosures to you, as a potential investor, please consider the following: The performance presented is not based on any actual securities trading, portfolio, or accounts, and the reported performance of the A, B, C, D, and F portfolios (collectively the “model portfolios”) should be considered mere “paper” or pro forma performance results based on Navellier’s research.
Investors evaluating any of Navellier & Associates, Inc.’s, (or its affiliates’) Investment Products must not use any information presented here, including the performance figures of the model portfolios, in their evaluation of any Navellier Investment Products. Navellier Investment Products include the firm’s mutual funds and managed accounts. The model portfolios, charts, and other information presented do not represent actual funded trades and are not actual funded portfolios. There are material differences between Navellier Investment Products’ portfolios and the model portfolios, research, and performance figures presented here. The model portfolios and the research results (1) may contain stocks or ETFs that are illiquid and difficult to trade; (2) may contain stock or ETF holdings materially different from actual funded Navellier Investment Product portfolios; (3) include the reinvestment of all dividends and other earnings, estimated trading costs, commissions, or management fees; and, (4) may not reflect prices obtained in an actual funded Navellier Investment Product portfolio. For these and other reasons, the reported performances of model portfolios do not reflect the performance results of Navellier’s actually funded and traded Investment Products. In most cases, Navellier’s Investment Products have materially lower performance results than the performances of the model portfolios presented.
This report contains statements that are, or may be considered to be, forward-looking statements. All statements that are not historical facts, including statements about our beliefs or expectations, are “forward-looking statements” within the meaning of The U.S. Private Securities Litigation Reform Act of 1995. These statements may be identified by such forward-looking terminology as “expect,” “estimate,” “plan,” “intend,” “believe,” “anticipate,” “may,” “will,” “should,” “could,” “continue,” “project,” or similar statements or variations of such terms. Our forward-looking statements are based on a series of expectations, assumptions, and projections, are not guarantees of future results or performance, and involve substantial risks and uncertainty as described in Form ADV Part 2A of our filing with the Securities and Exchange Commission (SEC), which is available at www.adviserinfo.sec.gov or by requesting a copy by emailing info@navellier.com. All of our forward-looking statements are as of the date of this report only. We can give no assurance that such expectations or forward-looking statements will prove to be correct. Actual results may differ materially. You are urged to carefully consider all such factors.
FEDERAL TAX ADVICE DISCLAIMER: As required by U.S. Treasury Regulations, you are informed that, to the extent this presentation includes any federal tax advice, the presentation is not written by Navellier to be used, and cannot be used, for the purpose of avoiding federal tax penalties. Navellier does not advise on any income tax requirements or issues. Use of any information presented by Navellier is for general information only and does not represent tax advice either express or implied. You are encouraged to seek professional tax advice for income tax questions and assistance.
IMPORTANT NEWSLETTER DISCLOSURE:The hypothetical performance results for investment newsletters that are authored or edited by Louis Navellier, including Louis Navellier’s Growth Investor, Louis Navellier’s Breakthrough Stocks, Louis Navellier’s Accelerated Profits, and Louis Navellier’s Platinum Club, are not based on any actual securities trading, portfolio, or accounts, and the newsletters’ reported hypothetical performances should be considered mere “paper” or proforma hypothetical performance results and are not actual performance of real world trades. Navellier & Associates, Inc. does not have any relation to or affiliation with the owner of these newsletters. There are material differences between Navellier Investment Products’ portfolios and the InvestorPlace Media, LLC newsletter portfolios authored by Louis Navellier. The InvestorPlace Media, LLC newsletters contain hypothetical performance that do not include transaction costs, advisory fees, or other fees a client might incur if actual investments and trades were being made by an investor. As a result, newsletter performance should not be used to evaluate Navellier Investment services which are separate and different from the newsletters. The owner of the newsletters is InvestorPlace Media, LLC and any questions concerning the newsletters, including any newsletter advertising or hypothetical Newsletter performance claims, (which are calculated solely by Investor Place Media and not Navellier) should be referred to InvestorPlace Media, LLC at (800) 718-8289.
Please note that Navellier & Associates and the Navellier Private Client Group are managed completely independent of the newsletters owned and published by InvestorPlace Media, LLC and written and edited by Louis Navellier, and investment performance of the newsletters should in no way be considered indicative of potential future investment performance for any Navellier & Associates separately managed account portfolio. Potential investors should consult with their financial advisor before investing in any Navellier Investment Product.
Navellier claims compliance with Global Investment Performance Standards (GIPS). To receive a complete list and descriptions of Navellier’s composites and/or a presentation that adheres to the GIPS standards, please contact Navellier or click here. It should not be assumed that any securities recommendations made by Navellier & Associates, Inc. in the future will be profitable or equal the performance of securities made in this report.
FactSet Disclosure: Navellier does not independently calculate the statistical information included in the attached report. The calculation and the information are provided by FactSet, a company not related to Navellier. Although information contained in the report has been obtained from FactSet and is based on sources Navellier believes to be reliable, Navellier does not guarantee its accuracy, and it may be incomplete or condensed. The report and the related FactSet sourced information are provided on an “as is” basis. The user assumes the entire risk of any use made of this information. Investors should consider the report as only a single factor in making their investment decision. The report is for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of a security. FactSet sourced information is the exclusive property of FactSet. Without prior written permission of FactSet, this information may not be reproduced, disseminated or used to create any financial products. All indices are unmanaged and performance of the indices include reinvestment of dividends and interest income, unless otherwise noted, are not illustrative of any particular investment and an investment cannot be made in any index. Past performance is no guarantee of future results.