by Jason Bodner
November 17, 2026
Nvidia was born in a San Jose Denny’s diner in 1993. Jensen Huang knew Denny’s well, because he was a teenage dishwasher and busboy at Denny’s. Years later, when Nvidia’s stock hit $100, he tattooed the company logo on his arm. On Thursday, 33-years after that first meeting at Denny’s, he resigned.
A year ago, headlines like that could have smacked the market down for a week. This time, the S&P 500 closed down 0.35%. How the market reacted tells us more about where we are than the headline does.
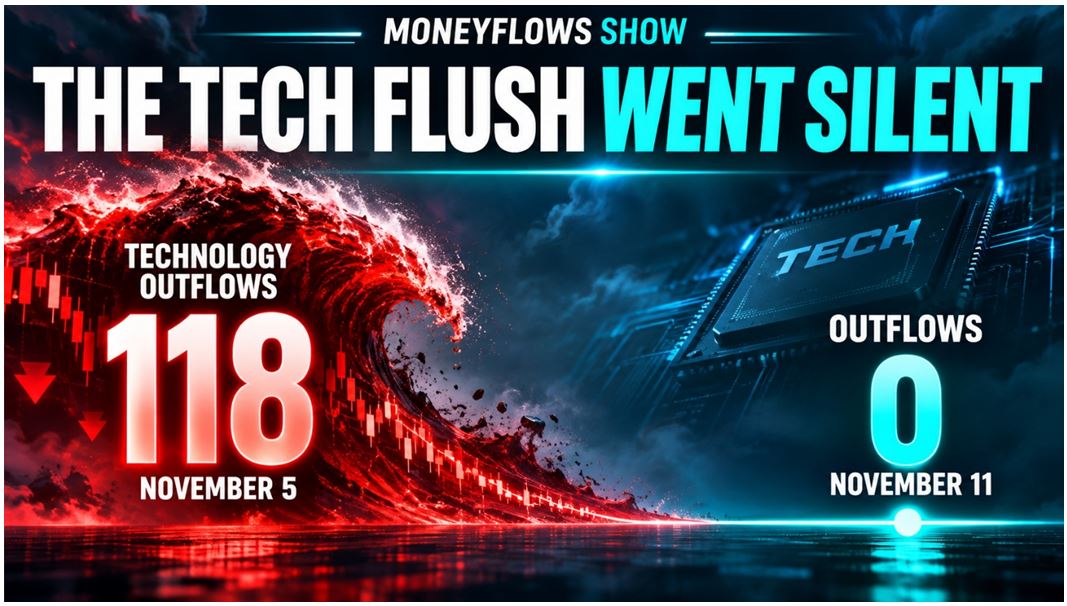
My view is that we’re in the final innings of a volatility washout. Technology data proves it. During the past 20-trading days, roughly 490-technology stocks had net outflows. That puts it in the top 7% of all such stretches since our technology data series began, in 2020. On November 5th alone, 118-technology stocks suffered outflows, the fifth-heaviest day on record, just behind the April 2025 tariff crash.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Since 2020, technology has seen an outflow wave this big only four other times. In three of them, technology stocks were higher six and nine-months later, with median gains of 25% and 35%. The last one came a year ago almost to the week, and technology rose 36% over the next six-months. The exception was December 2021.
So, what happens next? What separates a cycle bottom from a deeper drop?
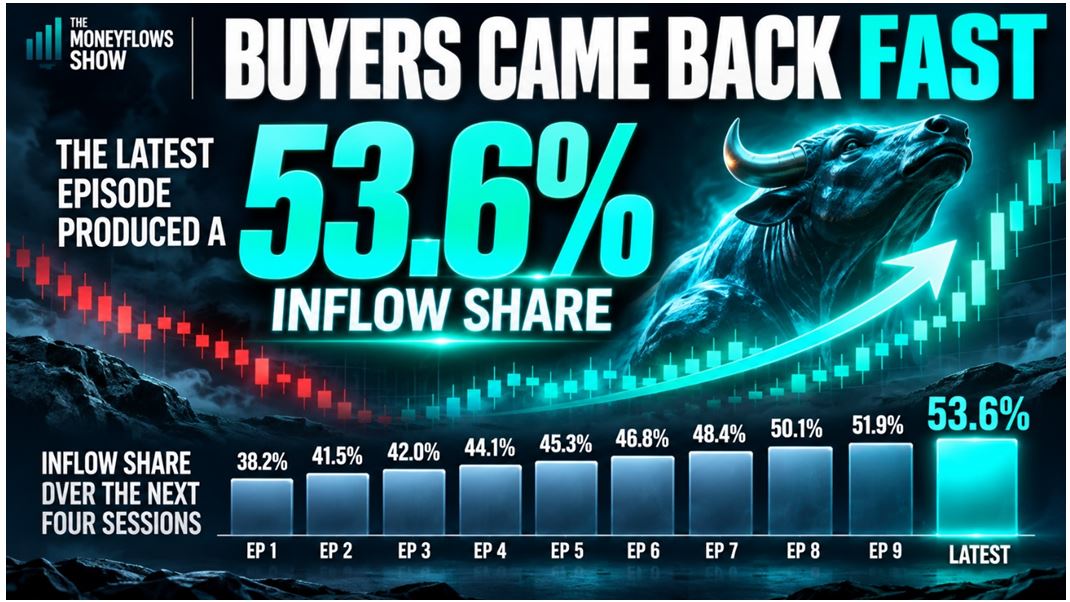
Since 2020, we’ve seen 10-days with 100 or more technology outflows. Usually outflows kept coming, often on a scale of 10 to 1 over the next four sessions. After November 5, inflows won, 37 to 32, a first in our data. The three closest matches, where inflows returned fastest, dipped the next week.
Three-months later, technology was higher each time, averaging 21%.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Outflows that just stop are what exhaustion looks like. Morgan Stanley says hedge funds cut risk at the fastest pace in more than a decade in early November. The forced sellers have already sold.
The Big Money Index (BMI) rose from 42.6% to 49.8% over the past week and went up every single day, including Nvidia’s bad news day. Consider that: The most important company in the AI trade lost its founder overnight. Its stock fell as much as 14% intraday and then closed down just 4.3%, so buyers took back more than two-thirds of the previous drop before the bell. The broad market barely moved. Other chipmakers rallied hard, and the money moved around inside AI instead of leaving it.
A market that’s still fragile breaks on news like that. A market that’s healing absorbs it.
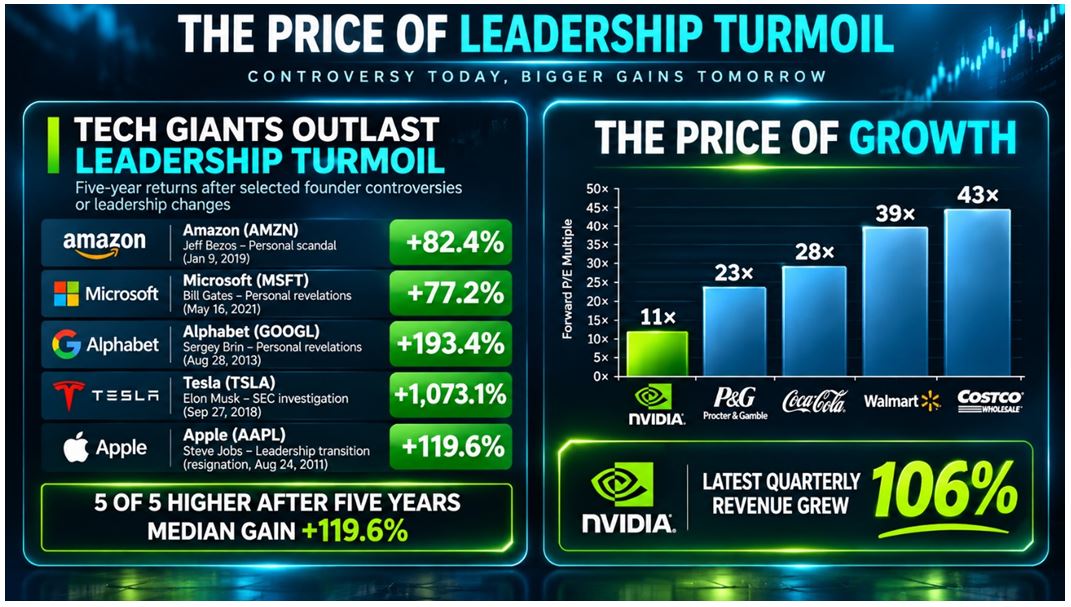
Yes, this scandal is serious, but it’s about one man’s personal behavior, not the business. History is on Nvidia’s side. I studied five-technology giants hit by founder scandals or major leadership changes. All five were higher two-years later, and all five were higher five-years later. Products and earnings outlasted the headlines. Today Nvidia trades at about 11-times forward earnings, its cheapest in 15-years, while revenue grows more than 100%. Costco trades at 43-times. Investors value groceries 4x the main engine of AI.
That gap won’t last.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Big money is leaving the fear trade. Where money goes matters as much as how much. Last week, our ETF data showed outflows from gold funds, bitcoin, ether funds and preferred stock funds. In stocks, energy drew zero inflows and 19 outflows, even with oil at $88. That’s investors taking off their hedges.
The inflows went into health care, industrials, utilities and consumer names. Technology is starting to come back too. It drew 33 inflows against 20 outflows last week, and on Wednesday every technology signal was an inflow. So far that’s software and internet names, not chips. When the semis join in, that’s the next confirmation.
The fastest growers are on sale. This is the part the fear crowd keeps missing. After 88% of the S&P 500 reported, FactSet says 84% of companies beat earnings and 74% beat revenue. Third-quarter earnings are up 31.4%. Yet the forward P/E fell to 17.7, below its 5-year average of 19.8.
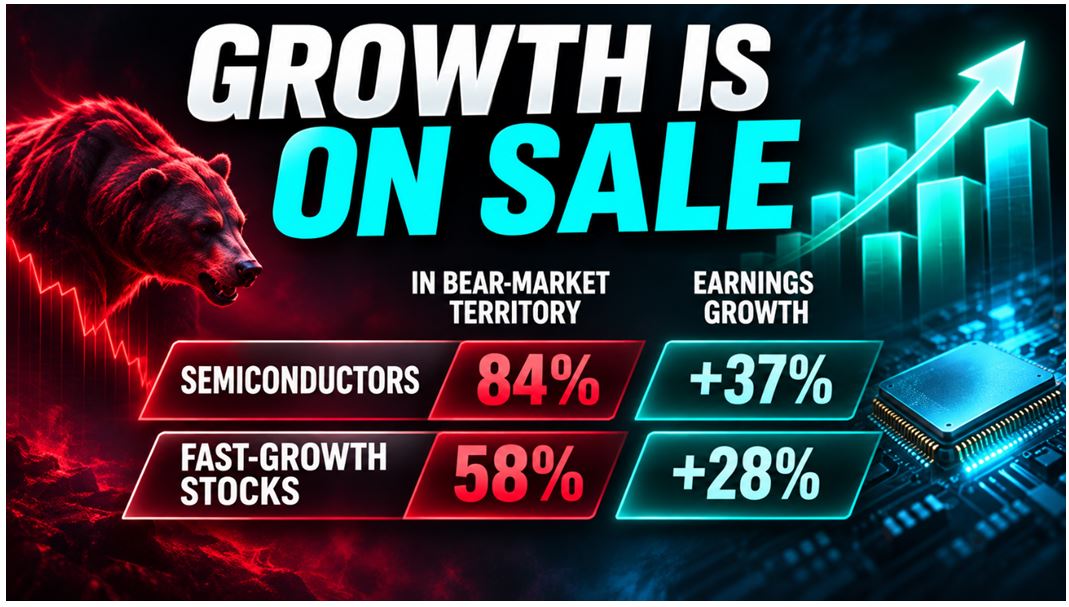
The real bargains are in growth. I screened every stock over $2 billion that’s growing both sales and earnings by 20% or more. Two-thirds of them are in bear markets, at a median 31% below their highs. Their earnings are growing 38%, nearly four-times the rest of the market. Semis are the extreme case: 84% are in bear markets while their earnings grow more than three-times faster than everything else.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
I also track a group of the fastest-growing AI infrastructure stocks. The median name is 49% below its high, yet its earnings are growing 30%. Since their recent lows, they’ve bounced a median 21%, nearly double the average stock. They’ve had big up days and quieter down days, with higher highs and higher lows. The names that got hit hardest are leading the recovery.
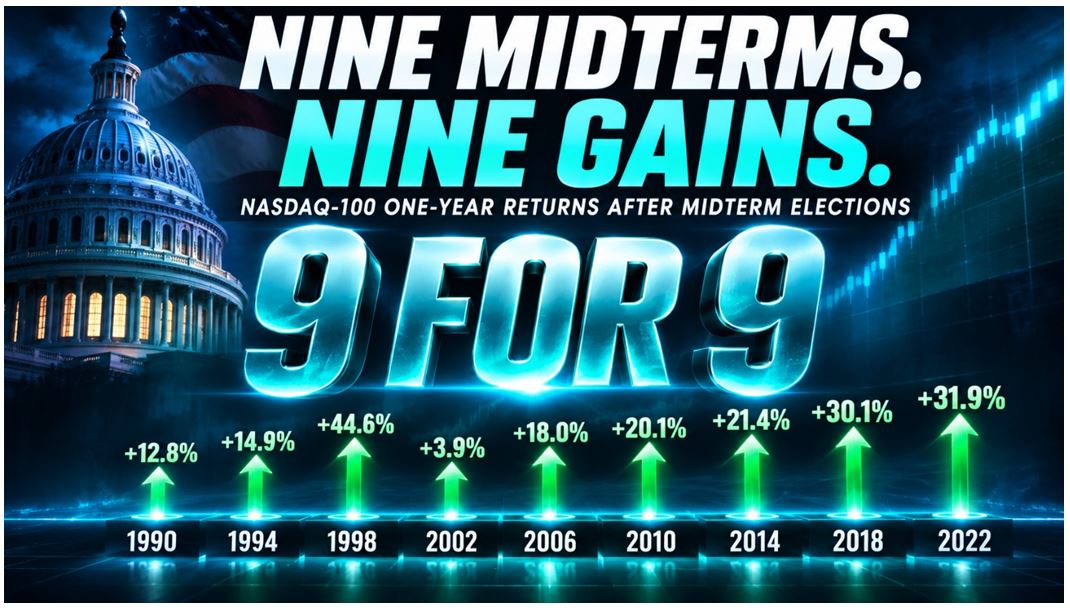
When the best growth is priced like it’s broken, the setup favors buyers. This is the stat I’d circle. I looked at where the S&P 500 went from November 12 of every midterm election year since 1990. Six-months later, it was higher every time. Nine-months later, every time. A year later, every time. That’s 9-for-9.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
The average one-year gain was 15.2%. Every year after November 12th, it was 10.7%. Midterm years are known for a rough middle and a strong finish, and we’re right on schedule. Stocks have spent about 78% of the time in bull markets since 1929. Pessimists may sound smart, but optimists make more money.
That doesn’t mean I’m ignoring risks. The 10-year Treasury rate hit 5.16% Friday, the Fed is hiking, and Nvidia reports Tuesday under a new acting CEO. Friday’s pullback fits the playbook. After big technology outflow days, the first-month has usually been choppy, but 3 to 9-months later technology was usually much higher. Outside technology, volume was light. Technology traded heavy, and that’s the tell to watch. If technology outflows return and the BMI rolls over, the market needs more time. Until then, a retest is right on schedule.
Bottom line, the headlines say be afraid, but the data says the clouds are parting. One company lost its founder, and the market digested that new reality. Technology flushed, then inflows won. The fastest growers are priced like they’re broken, and every midterm November since 1990 led to a higher market a year later.
And finally, let me say it has been a distinct honor and privilege to share this journey with you over the past 11-years. I look forward to continuing our conversation at MoneyFlows.com, where you’ll find my commentary in the “Latest Insights” section.
“Every new beginning comes from some other beginning’s end.” – Seneca
All content above represents the opinion of Jason Bodner of Navellier & Associates, Inc.
Also In This Issue
A Look Ahead by Louis Navellier
The Latest News from Nvidia and Other Leading Tech Companies
Income Mail by Bryan Perry
AI’s Disinflationary Power Fuels a Virtuous Cycle
Growth Mail by Gary Alexander
Investment Lessons After Nearly 60 Years in the Game
Global Mail by Ivan Martchev
Nvidia’s $2 Trillion Soap Opera
Sector Spotlight by Jason Bodner
The Washout Is Done. History Says “Look Up”
Important Disclosures:
Jason Bodner is a co-founder and co-owner of Mapsignals. Mr. Bodner is an independent contractor who is occasionally hired by Navellier & Associates to write an article and or provide opinions for possible use in articles that appear in Navellier & Associates weekly Market Mail. Mr. Bodner is not employed or affiliated with Louis Navellier, Navellier & Associates, Inc., or any other Navellier owned entity. The opinions and statements made here are those of Mr. Bodner and not necessarily those of any other persons or entities. This is not an endorsement, or solicitation or testimonial or investment advice regarding the BMI Index or any statements or recommendations or analysis in the article or the BMI Index or Mapsignals or its products or strategies.
Although information in these reports has been obtained from and is based upon sources that Navellier believes to be reliable, Navellier does not guarantee its accuracy and it may be incomplete or condensed. All opinions and estimates constitute Navellier’s judgment as of the date the report was created and are subject to change without notice. These reports are for informational purposes only and are not a solicitation for the purchase or sale of a security. Any decision to purchase securities mentioned in these reports must take into account existing public information on such securities or any registered prospectus.To the extent permitted by law, neither Navellier & Associates, Inc., nor any of its affiliates, agents, or service providers assumes any liability or responsibility nor owes any duty of care for any consequences of any person acting or refraining to act in reliance on the information contained in this communication or for any decision based on it.
Past performance is no indication of future results. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. It should not be assumed that any securities recommendations made by Navellier. in the future will be profitable or equal the performance of securities made in this report. Dividend payments are not guaranteed. The amount of a dividend payment, if any, can vary over time and issuers may reduce dividends paid on securities in the event of a recession or adverse event affecting a specific industry or issuer.
None of the stock information, data, and company information presented herein constitutes a recommendation by Navellier or a solicitation to buy or sell any securities. Any specific securities identified and described do not represent all of the securities purchased, sold, or recommended for advisory clients. The holdings identified do not represent all of the securities purchased, sold, or recommended for advisory clients and the reader should not assume that investments in the securities identified and discussed were or will be profitable.
Information presented is general information that does not take into account your individual circumstances, financial situation, or needs, nor does it present a personalized recommendation to you. Individual stocks presented may not be suitable for every investor. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. Investment in fixed income securities has the potential for the investment return and principal value of an investment to fluctuate so that an investor’s holdings, when redeemed, may be worth less than their original cost.
One cannot invest directly in an index. Index is unmanaged and index performance does not reflect deduction of fees, expenses, or taxes. Presentation of Index data does not reflect a belief by Navellier that any stock index constitutes an investment alternative to any Navellier equity strategy or is necessarily comparable to such strategies. Among the most important differences between the Indices and Navellier strategies are that the Navellier equity strategies may (1) incur material management fees, (2) concentrate its investments in relatively few stocks, industries, or sectors, (3) have significantly greater trading activity and related costs, and (4) be significantly more or less volatile than the Indices.
ETF Risk: We may invest in exchange traded funds (“ETFs”) and some of our investment strategies are generally fully invested in ETFs. Like traditional mutual funds, ETFs charge asset-based fees, but they generally do not charge initial sales charges or redemption fees and investors typically pay only customary brokerage fees to buy and sell ETF shares. The fees and costs charged by ETFs held in client accounts will not be deducted from the compensation the client pays Navellier. ETF prices can fluctuate up or down, and a client account could lose money investing in an ETF if the prices of the securities owned by the ETF go down. ETFs are subject to additional risks:
- ETF shares may trade above or below their net asset value;
- An active trading market for an ETF’s shares may not develop or be maintained;
- The value of an ETF may be more volatile than the underlying portfolio of securities the ETF is designed to track;
- The cost of owning shares of the ETF may exceed those a client would incur by directly investing in the underlying securities and;
- Trading of an ETF’s shares may be halted if the listing exchange’s officials deem it appropriate, the shares are delisted from the exchange, or the activation of market-wide “circuit breakers” (which are tied to large decreases in stock prices) halts stock trading generally.
Grader Disclosures: Investment in equity strategies involves substantial risk and has the potential for partial or complete loss of funds invested. The sample portfolio and any accompanying charts are for informational purposes only and are not to be construed as a solicitation to buy or sell any financial instrument and should not be relied upon as the sole factor in an investment making decision. As a matter of normal and important disclosures to you, as a potential investor, please consider the following: The performance presented is not based on any actual securities trading, portfolio, or accounts, and the reported performance of the A, B, C, D, and F portfolios (collectively the “model portfolios”) should be considered mere “paper” or pro forma performance results based on Navellier’s research.
Investors evaluating any of Navellier & Associates, Inc.’s, (or its affiliates’) Investment Products must not use any information presented here, including the performance figures of the model portfolios, in their evaluation of any Navellier Investment Products. Navellier Investment Products include the firm’s mutual funds and managed accounts. The model portfolios, charts, and other information presented do not represent actual funded trades and are not actual funded portfolios. There are material differences between Navellier Investment Products’ portfolios and the model portfolios, research, and performance figures presented here. The model portfolios and the research results (1) may contain stocks or ETFs that are illiquid and difficult to trade; (2) may contain stock or ETF holdings materially different from actual funded Navellier Investment Product portfolios; (3) include the reinvestment of all dividends and other earnings, estimated trading costs, commissions, or management fees; and, (4) may not reflect prices obtained in an actual funded Navellier Investment Product portfolio. For these and other reasons, the reported performances of model portfolios do not reflect the performance results of Navellier’s actually funded and traded Investment Products. In most cases, Navellier’s Investment Products have materially lower performance results than the performances of the model portfolios presented.
This report contains statements that are, or may be considered to be, forward-looking statements. All statements that are not historical facts, including statements about our beliefs or expectations, are “forward-looking statements” within the meaning of The U.S. Private Securities Litigation Reform Act of 1995. These statements may be identified by such forward-looking terminology as “expect,” “estimate,” “plan,” “intend,” “believe,” “anticipate,” “may,” “will,” “should,” “could,” “continue,” “project,” or similar statements or variations of such terms. Our forward-looking statements are based on a series of expectations, assumptions, and projections, are not guarantees of future results or performance, and involve substantial risks and uncertainty as described in Form ADV Part 2A of our filing with the Securities and Exchange Commission (SEC), which is available at www.adviserinfo.sec.gov or by requesting a copy by emailing info@navellier.com. All of our forward-looking statements are as of the date of this report only. We can give no assurance that such expectations or forward-looking statements will prove to be correct. Actual results may differ materially. You are urged to carefully consider all such factors.
FEDERAL TAX ADVICE DISCLAIMER: As required by U.S. Treasury Regulations, you are informed that, to the extent this presentation includes any federal tax advice, the presentation is not written by Navellier to be used, and cannot be used, for the purpose of avoiding federal tax penalties. Navellier does not advise on any income tax requirements or issues. Use of any information presented by Navellier is for general information only and does not represent tax advice either express or implied. You are encouraged to seek professional tax advice for income tax questions and assistance.
IMPORTANT NEWSLETTER DISCLOSURE:The hypothetical performance results for investment newsletters that are authored or edited by Louis Navellier, including Louis Navellier’s Growth Investor, Louis Navellier’s Breakthrough Stocks, Louis Navellier’s Accelerated Profits, and Louis Navellier’s Platinum Club, are not based on any actual securities trading, portfolio, or accounts, and the newsletters’ reported hypothetical performances should be considered mere “paper” or proforma hypothetical performance results and are not actual performance of real world trades. Navellier & Associates, Inc. does not have any relation to or affiliation with the owner of these newsletters. There are material differences between Navellier Investment Products’ portfolios and the InvestorPlace Media, LLC newsletter portfolios authored by Louis Navellier. The InvestorPlace Media, LLC newsletters contain hypothetical performance that do not include transaction costs, advisory fees, or other fees a client might incur if actual investments and trades were being made by an investor. As a result, newsletter performance should not be used to evaluate Navellier Investment services which are separate and different from the newsletters. The owner of the newsletters is InvestorPlace Media, LLC and any questions concerning the newsletters, including any newsletter advertising or hypothetical Newsletter performance claims, (which are calculated solely by Investor Place Media and not Navellier) should be referred to InvestorPlace Media, LLC at (800) 718-8289.
Please note that Navellier & Associates and the Navellier Private Client Group are managed completely independent of the newsletters owned and published by InvestorPlace Media, LLC and written and edited by Louis Navellier, and investment performance of the newsletters should in no way be considered indicative of potential future investment performance for any Navellier & Associates separately managed account portfolio. Potential investors should consult with their financial advisor before investing in any Navellier Investment Product.
Navellier claims compliance with Global Investment Performance Standards (GIPS). To receive a complete list and descriptions of Navellier’s composites and/or a presentation that adheres to the GIPS standards, please contact Navellier or click here. It should not be assumed that any securities recommendations made by Navellier & Associates, Inc. in the future will be profitable or equal the performance of securities made in this report.
FactSet Disclosure: Navellier does not independently calculate the statistical information included in the attached report. The calculation and the information are provided by FactSet, a company not related to Navellier. Although information contained in the report has been obtained from FactSet and is based on sources Navellier believes to be reliable, Navellier does not guarantee its accuracy, and it may be incomplete or condensed. The report and the related FactSet sourced information are provided on an “as is” basis. The user assumes the entire risk of any use made of this information. Investors should consider the report as only a single factor in making their investment decision. The report is for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of a security. FactSet sourced information is the exclusive property of FactSet. Without prior written permission of FactSet, this information may not be reproduced, disseminated or used to create any financial products. All indices are unmanaged and performance of the indices include reinvestment of dividends and interest income, unless otherwise noted, are not illustrative of any particular investment and an investment cannot be made in any index. Past performance is no guarantee of future results.