by Jason Bodner
October 6, 2026
At the end of October, Daylight Savings Time will end, and our sunsets will come earlier each day until December 21 – the shortest day of the year – but that’s not the coldest day of winter – it’s not even close.
East of the Rockies, the coldest stretch usually shows up about a month later, in late January. Land, air and water hold on to heat, so it takes weeks for the lost sunlight to catch up. Scientists call this seasonal lag. The reality is summed up in this aphorism: “When the days get longer, the cold gets stronger.”
Here’s the game plan in weather patterns: The sun hides first, then the thermometer catches up later.
Markets work in a similar way. I think we’re very close to the market’s winter solstice right now. But it may not be “the” bottom” of some of the specific market indexes we follow.
The Indexes Haven’t Felt the Cold… Yet
If you only watched the headlines, you’d think everything was fine. The S&P 500 approached new highs last week and now sits just 1.7% below its August high. The NASDAQ 100 is even closer to its peak level.
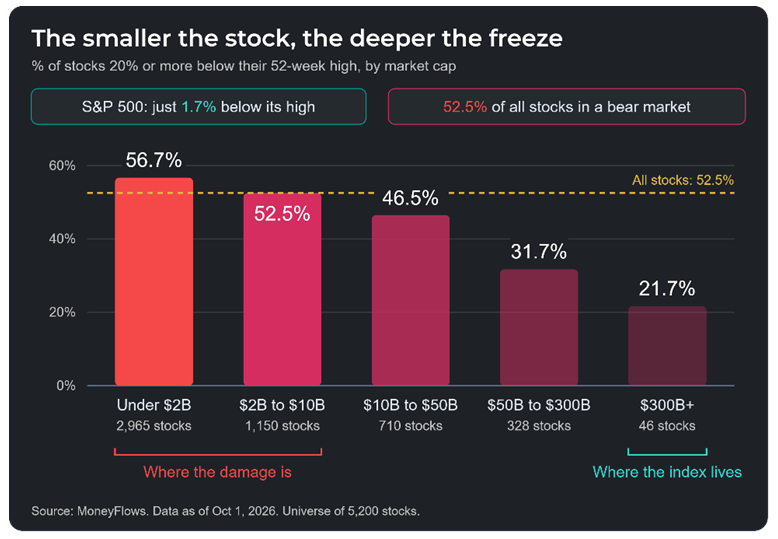
Those are the indexes, but the market underneath them tells a different story. For instance, the Russell 2000 is now 8.5% off its high. The smaller the company, the worse it gets. Among stocks under $2 billion market cap, 57% are in a bear market. For giants worth over $300 billion, it’s just 22%. Of the 5,000+ stocks we track, 52.5% of them sit 20% or more below their highs, meaning over half of all stocks are in a bear market. A handful of huge names are holding the index up while everything beneath them freezes.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Selling in Late September Sent the Big Money Index Down Near “Oversold” Territory
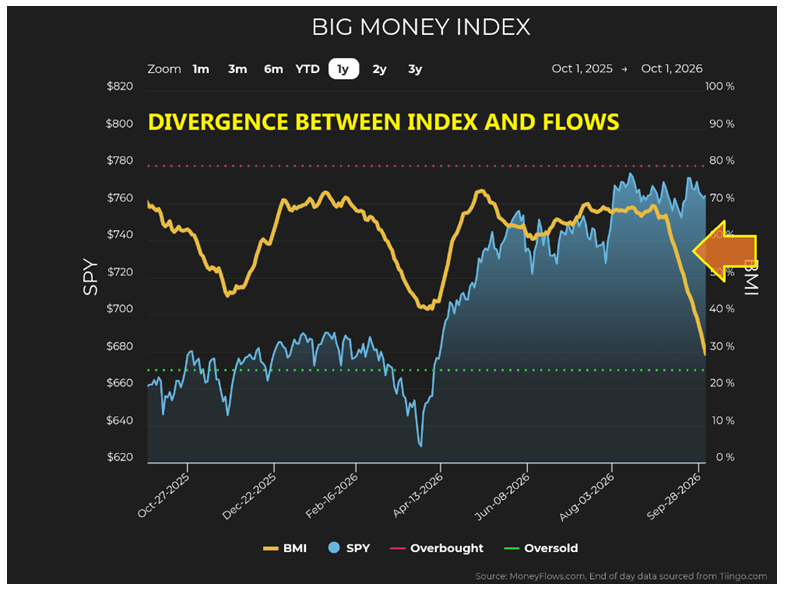
The Big Money Index (BMI) tracks big institutional buying and selling. Above 80% is overbought, and below 25% is oversold. Last Thursday, it hit 29.3%. Since 1993, the BMI has never been below 30% with the S&P this close to a record. The VIX fear gauge is just 16, while the pain is being felt in the stocks.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
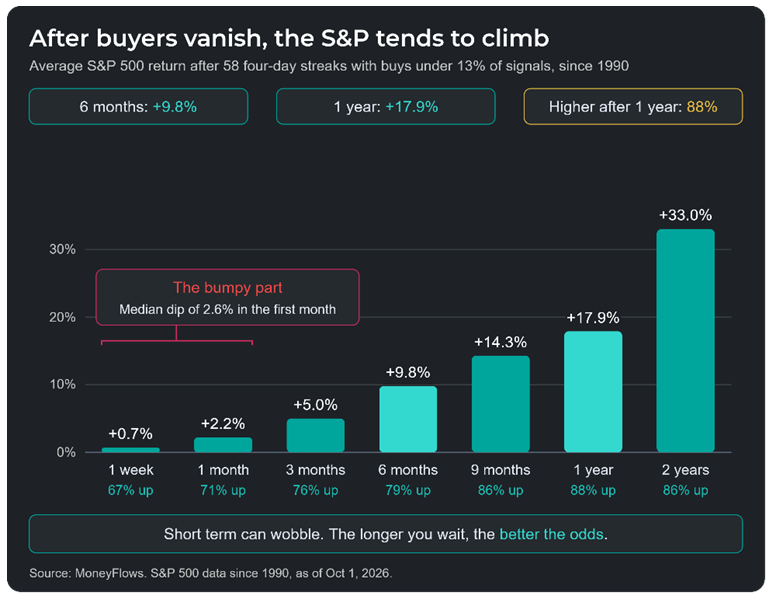
Last week, buying nearly dried up. For four-straight days, inflows were less than 13% of all signals. We’ve seen 58-streaks like that since 1990. The S&P was never this close to its high during any of them.
Historically, what came next was strong. Six-months later, the S&P averaged a 9.8% gain. A year later, it gained an average 17.9% and it was higher 88% of the time, but the weeks right after can still be bumpy.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
ETFs told us the same story, with 100 or more outflows four-days in a row. That ties the record. It happened only three-times before: December 2018, September 2022 and April 2025. All three came at or near major lows. A year later, the S&P was up between 20% and 40% each time.
Sector Spotlight: The Last Shelter Cracks
All sectors suffered net outflows last week. In the previous week, technology was the lone exception.
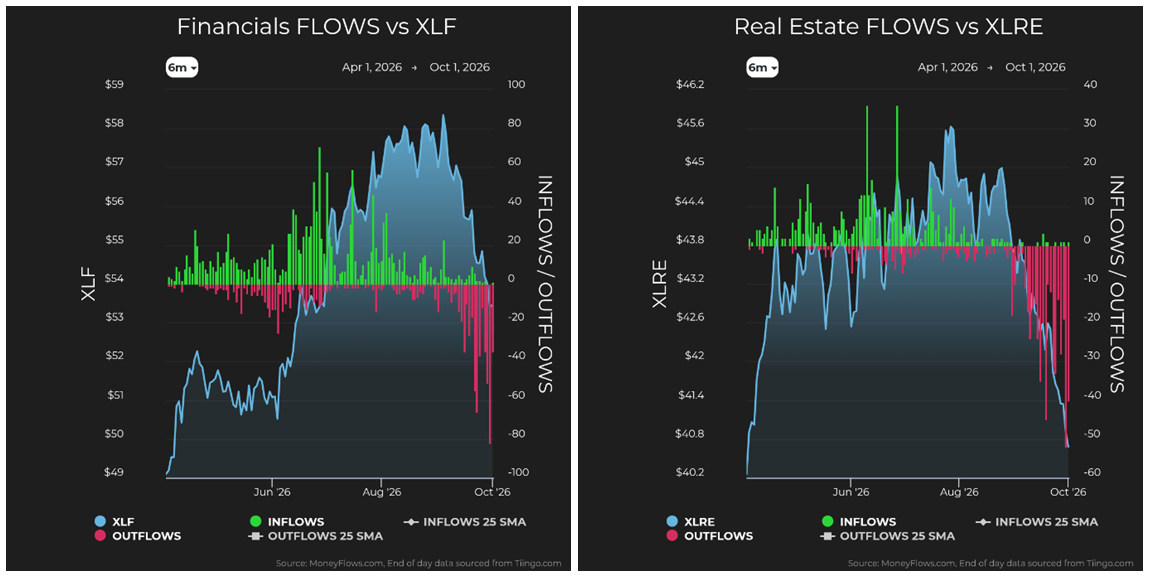
Financials got hit hardest, with 203 outflows vs. just three inflows. Banks alone saw 100 outflows, with no inflows. Before last week, financials were the market’s hiding spot. They have the fewest stocks in a bear market of any sector, and the most near their highs. Now, that last safe spot got hammered too.
 Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
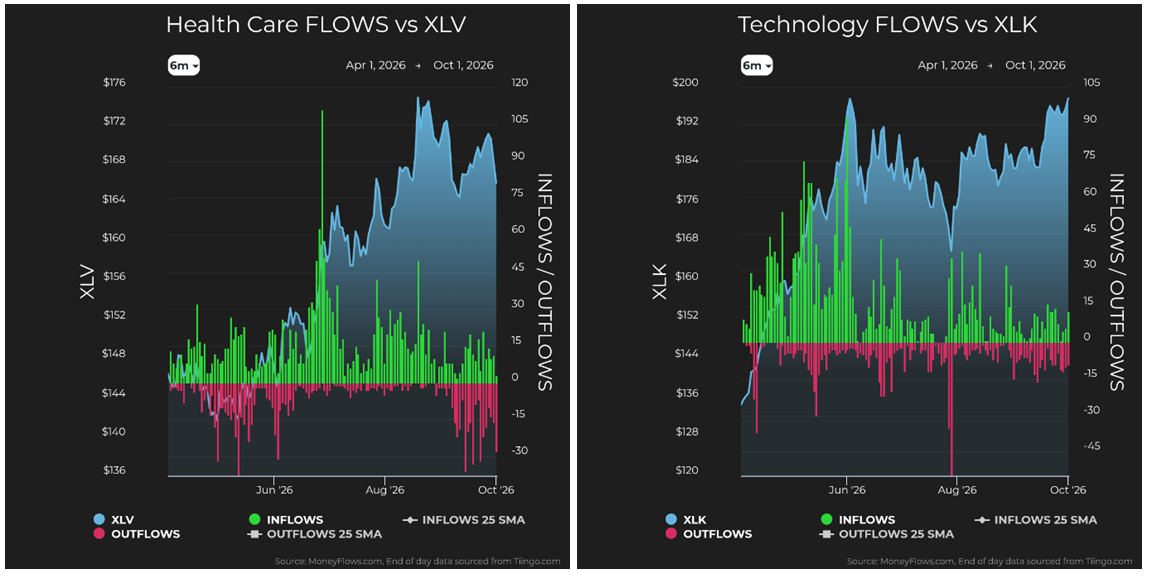
Real estate came next with 139 outflows, nearly all REITs. Hotels, restaurants and leisure stocks saw 47 outflows and zero inflows. Dividend payers still foot the bill. The median stock sold pays a 2.4% yield. The median stock bought pays nothing. The money is going toward Health care, which led all sectors with 38 inflows, mostly in lab tools and genetic testing names.
Then there’s AI… Since the July and August lows, smaller tech stocks worth $1 billion to $50 billion are up a median 18%. Similar-sized stocks outside tech are up just 3%. Chip equipment makers lead the way, up 28% from their lows. Big money kept buying these names even during this week’s flush. Still, 64% of these smaller technology stocks are in bear markets, so they have plenty of room to run.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
Has Peak Rate Fear Passed?
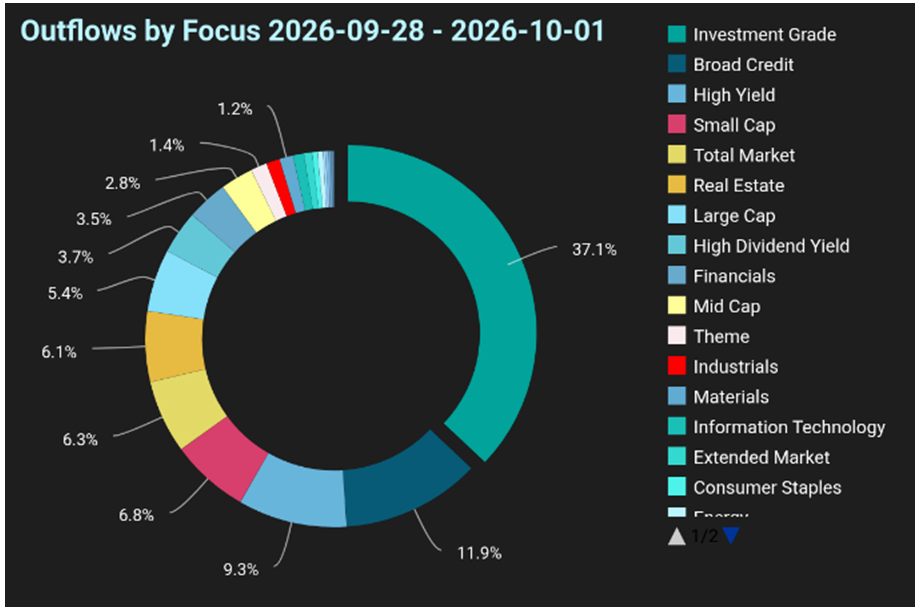
Much of this comes back to interest rates, as investors worried the Fed might hike again. Last week, that worry hit the bond market. Bond ETFs saw 250 outflows in four-days, more than stock ETFs. Long-term Treasury funds got sold every day. The only bonds anyone wanted were short-term (cash-like) funds.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
When investors dump long bonds this broadly, the fear of rising rates is often close to peaking. Friday’s weak jobs report added to that case, and it will be hard for the Fed to hike rates into a soft job market.
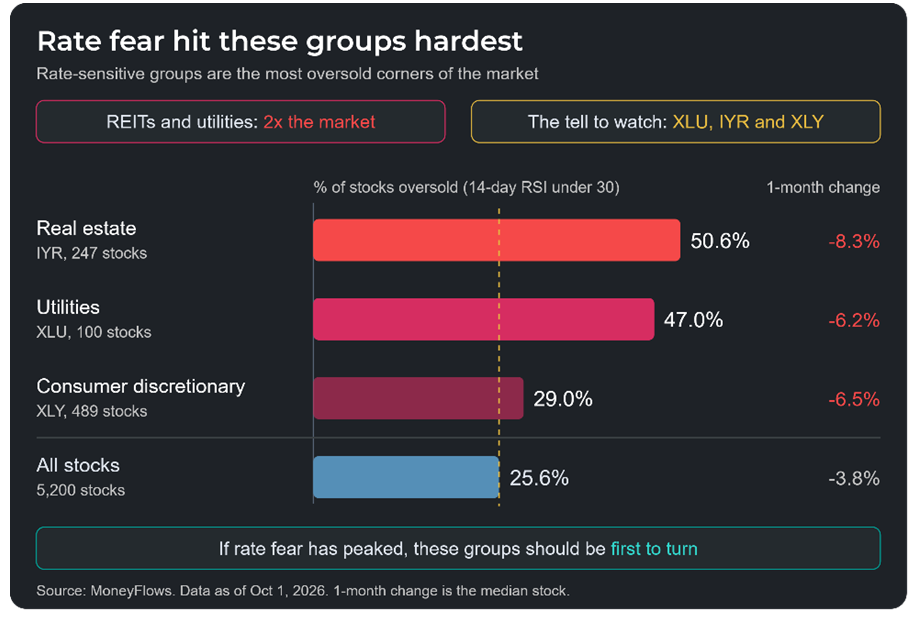
If rate fear has peaked, we’ll see it first in the groups hurt most by high rates. Utilities and real estate are both yielding sectors sensitive to rates while discretionary are sensitive to consumer spending with constrictive rates. About half of all REIT and utility stocks are technically oversold, roughly double the rate for the overall market. When the selling in these groups dries up and buying shows up, that’s our tell.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
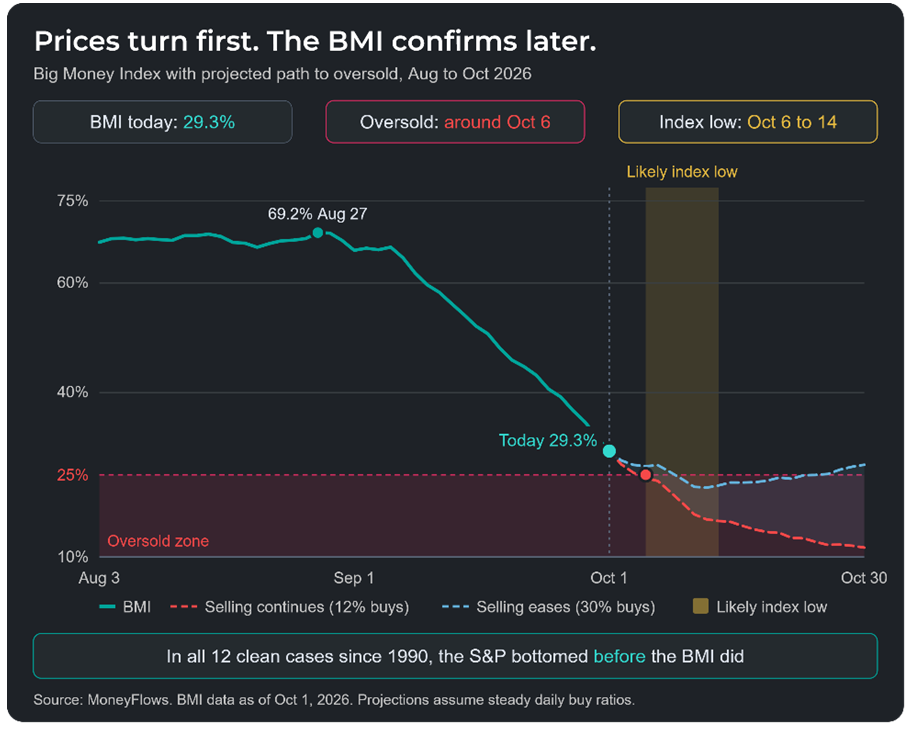
The BMI is a 25-day average, so it lags by design. It keeps getting colder after prices have already turned. At its current pace, the BMI should reach oversold this week, perhaps today, or around October 6.
That’s not necessarily the end of the decline. The BMI could keep falling for another week after that.
History says not to wait for it, though. In 12-oversold episodes since 1990, the S&P’s low came within a week of the BMI’s low. In all 12-episodes, the S&P bottomed first. By the time the BMI hit bottom, the S&P had usually bounced back by about 2%.
That puts a likely low for the market over the next week or so, October 6 to 14. That also lines up with the midterm election calendar. Since 1990, seven of nine midterm fall lows landed in the first half of October.
Graphs are for illustrative and discussion purposes only. Please read important disclosures at the end of this commentary.
There’s one warning. In 2018, the S&P also sat near a high when the BMI went oversold. It fell another 11% into December as the Fed kept hiking rates, at least once too often. That’s why rates could be the key to the bottom this time. If peak rate fear is behind us, history leans toward a quick finish.
So far, the major indexes haven’t felt the cold. The market underneath took all of it. But the days are already getting longer, and the turn usually shows up before anyone sounds the all-clear.
“No winter lasts forever; no spring skips its turn.” – Hal Borland
All content above represents the opinion of Jason Bodner of Navellier & Associates, Inc.
Also In This Issue
A Look Ahead by Louis Navellier
The Fourth Quarter is When Stocks Usually Shine the Brightest
Income Mail by Bryan Perry
The Bond Market Deserves a Sigh of Relief
Growth Mail by Gary Alexander
The Current AI Scare Resembles Past Techno-Terror Tales
Global Mail by Ivan Martchev
Sector Friction in the S&P 500 Widens
Sector Spotlight by Jason Bodner
Like the Seasons, Markets Often Wax and Wane on Schedule
View Full Archive
Read Past Issues Here
Jason Bodner
MARKETMAIL EDITOR FOR SECTOR SPOTLIGHT
Jason Bodner writes Sector Spotlight in the weekly Marketmail publication and has authored several white papers for the company. He is also Co-Founder of Macro Analytics for Professionals which produces proprietary equity accumulation and distribution research for its clients. Previously, Mr. Bodner served as Director of European Equity Derivatives for Cantor Fitzgerald Europe in London, then moved to the role of Head of Equity Derivatives North America for the same company in New York. He also served as S.V.P. Equity Derivatives for Jefferies, LLC. He received a B.S. in business administration in 1996, with honors, from Skidmore College as a member of the Periclean Honors Society. All content of “Sector Spotlight” represents the opinion of Jason Bodner
Important Disclosures:
Jason Bodner is a co-founder and co-owner of Mapsignals. Mr. Bodner is an independent contractor who is occasionally hired by Navellier & Associates to write an article and or provide opinions for possible use in articles that appear in Navellier & Associates weekly Market Mail. Mr. Bodner is not employed or affiliated with Louis Navellier, Navellier & Associates, Inc., or any other Navellier owned entity. The opinions and statements made here are those of Mr. Bodner and not necessarily those of any other persons or entities. This is not an endorsement, or solicitation or testimonial or investment advice regarding the BMI Index or any statements or recommendations or analysis in the article or the BMI Index or Mapsignals or its products or strategies.
Although information in these reports has been obtained from and is based upon sources that Navellier believes to be reliable, Navellier does not guarantee its accuracy and it may be incomplete or condensed. All opinions and estimates constitute Navellier’s judgment as of the date the report was created and are subject to change without notice. These reports are for informational purposes only and are not a solicitation for the purchase or sale of a security. Any decision to purchase securities mentioned in these reports must take into account existing public information on such securities or any registered prospectus.To the extent permitted by law, neither Navellier & Associates, Inc., nor any of its affiliates, agents, or service providers assumes any liability or responsibility nor owes any duty of care for any consequences of any person acting or refraining to act in reliance on the information contained in this communication or for any decision based on it.
Past performance is no indication of future results. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. It should not be assumed that any securities recommendations made by Navellier. in the future will be profitable or equal the performance of securities made in this report. Dividend payments are not guaranteed. The amount of a dividend payment, if any, can vary over time and issuers may reduce dividends paid on securities in the event of a recession or adverse event affecting a specific industry or issuer.
None of the stock information, data, and company information presented herein constitutes a recommendation by Navellier or a solicitation to buy or sell any securities. Any specific securities identified and described do not represent all of the securities purchased, sold, or recommended for advisory clients. The holdings identified do not represent all of the securities purchased, sold, or recommended for advisory clients and the reader should not assume that investments in the securities identified and discussed were or will be profitable.
Information presented is general information that does not take into account your individual circumstances, financial situation, or needs, nor does it present a personalized recommendation to you. Individual stocks presented may not be suitable for every investor. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. Investment in fixed income securities has the potential for the investment return and principal value of an investment to fluctuate so that an investor’s holdings, when redeemed, may be worth less than their original cost.
One cannot invest directly in an index. Index is unmanaged and index performance does not reflect deduction of fees, expenses, or taxes. Presentation of Index data does not reflect a belief by Navellier that any stock index constitutes an investment alternative to any Navellier equity strategy or is necessarily comparable to such strategies. Among the most important differences between the Indices and Navellier strategies are that the Navellier equity strategies may (1) incur material management fees, (2) concentrate its investments in relatively few stocks, industries, or sectors, (3) have significantly greater trading activity and related costs, and (4) be significantly more or less volatile than the Indices.
ETF Risk: We may invest in exchange traded funds (“ETFs”) and some of our investment strategies are generally fully invested in ETFs. Like traditional mutual funds, ETFs charge asset-based fees, but they generally do not charge initial sales charges or redemption fees and investors typically pay only customary brokerage fees to buy and sell ETF shares. The fees and costs charged by ETFs held in client accounts will not be deducted from the compensation the client pays Navellier. ETF prices can fluctuate up or down, and a client account could lose money investing in an ETF if the prices of the securities owned by the ETF go down. ETFs are subject to additional risks:
- ETF shares may trade above or below their net asset value;
- An active trading market for an ETF’s shares may not develop or be maintained;
- The value of an ETF may be more volatile than the underlying portfolio of securities the ETF is designed to track;
- The cost of owning shares of the ETF may exceed those a client would incur by directly investing in the underlying securities and;
- Trading of an ETF’s shares may be halted if the listing exchange’s officials deem it appropriate, the shares are delisted from the exchange, or the activation of market-wide “circuit breakers” (which are tied to large decreases in stock prices) halts stock trading generally.
Grader Disclosures: Investment in equity strategies involves substantial risk and has the potential for partial or complete loss of funds invested. The sample portfolio and any accompanying charts are for informational purposes only and are not to be construed as a solicitation to buy or sell any financial instrument and should not be relied upon as the sole factor in an investment making decision. As a matter of normal and important disclosures to you, as a potential investor, please consider the following: The performance presented is not based on any actual securities trading, portfolio, or accounts, and the reported performance of the A, B, C, D, and F portfolios (collectively the “model portfolios”) should be considered mere “paper” or pro forma performance results based on Navellier’s research.
Investors evaluating any of Navellier & Associates, Inc.’s, (or its affiliates’) Investment Products must not use any information presented here, including the performance figures of the model portfolios, in their evaluation of any Navellier Investment Products. Navellier Investment Products include the firm’s mutual funds and managed accounts. The model portfolios, charts, and other information presented do not represent actual funded trades and are not actual funded portfolios. There are material differences between Navellier Investment Products’ portfolios and the model portfolios, research, and performance figures presented here. The model portfolios and the research results (1) may contain stocks or ETFs that are illiquid and difficult to trade; (2) may contain stock or ETF holdings materially different from actual funded Navellier Investment Product portfolios; (3) include the reinvestment of all dividends and other earnings, estimated trading costs, commissions, or management fees; and, (4) may not reflect prices obtained in an actual funded Navellier Investment Product portfolio. For these and other reasons, the reported performances of model portfolios do not reflect the performance results of Navellier’s actually funded and traded Investment Products. In most cases, Navellier’s Investment Products have materially lower performance results than the performances of the model portfolios presented.
This report contains statements that are, or may be considered to be, forward-looking statements. All statements that are not historical facts, including statements about our beliefs or expectations, are “forward-looking statements” within the meaning of The U.S. Private Securities Litigation Reform Act of 1995. These statements may be identified by such forward-looking terminology as “expect,” “estimate,” “plan,” “intend,” “believe,” “anticipate,” “may,” “will,” “should,” “could,” “continue,” “project,” or similar statements or variations of such terms. Our forward-looking statements are based on a series of expectations, assumptions, and projections, are not guarantees of future results or performance, and involve substantial risks and uncertainty as described in Form ADV Part 2A of our filing with the Securities and Exchange Commission (SEC), which is available at www.adviserinfo.sec.gov or by requesting a copy by emailing info@navellier.com. All of our forward-looking statements are as of the date of this report only. We can give no assurance that such expectations or forward-looking statements will prove to be correct. Actual results may differ materially. You are urged to carefully consider all such factors.
FEDERAL TAX ADVICE DISCLAIMER: As required by U.S. Treasury Regulations, you are informed that, to the extent this presentation includes any federal tax advice, the presentation is not written by Navellier to be used, and cannot be used, for the purpose of avoiding federal tax penalties. Navellier does not advise on any income tax requirements or issues. Use of any information presented by Navellier is for general information only and does not represent tax advice either express or implied. You are encouraged to seek professional tax advice for income tax questions and assistance.
IMPORTANT NEWSLETTER DISCLOSURE:The hypothetical performance results for investment newsletters that are authored or edited by Louis Navellier, including Louis Navellier’s Growth Investor, Louis Navellier’s Breakthrough Stocks, Louis Navellier’s Accelerated Profits, and Louis Navellier’s Platinum Club, are not based on any actual securities trading, portfolio, or accounts, and the newsletters’ reported hypothetical performances should be considered mere “paper” or proforma hypothetical performance results and are not actual performance of real world trades. Navellier & Associates, Inc. does not have any relation to or affiliation with the owner of these newsletters. There are material differences between Navellier Investment Products’ portfolios and the InvestorPlace Media, LLC newsletter portfolios authored by Louis Navellier. The InvestorPlace Media, LLC newsletters contain hypothetical performance that do not include transaction costs, advisory fees, or other fees a client might incur if actual investments and trades were being made by an investor. As a result, newsletter performance should not be used to evaluate Navellier Investment services which are separate and different from the newsletters. The owner of the newsletters is InvestorPlace Media, LLC and any questions concerning the newsletters, including any newsletter advertising or hypothetical Newsletter performance claims, (which are calculated solely by Investor Place Media and not Navellier) should be referred to InvestorPlace Media, LLC at (800) 718-8289.
Please note that Navellier & Associates and the Navellier Private Client Group are managed completely independent of the newsletters owned and published by InvestorPlace Media, LLC and written and edited by Louis Navellier, and investment performance of the newsletters should in no way be considered indicative of potential future investment performance for any Navellier & Associates separately managed account portfolio. Potential investors should consult with their financial advisor before investing in any Navellier Investment Product.
Navellier claims compliance with Global Investment Performance Standards (GIPS). To receive a complete list and descriptions of Navellier’s composites and/or a presentation that adheres to the GIPS standards, please contact Navellier or click here. It should not be assumed that any securities recommendations made by Navellier & Associates, Inc. in the future will be profitable or equal the performance of securities made in this report.
FactSet Disclosure: Navellier does not independently calculate the statistical information included in the attached report. The calculation and the information are provided by FactSet, a company not related to Navellier. Although information contained in the report has been obtained from FactSet and is based on sources Navellier believes to be reliable, Navellier does not guarantee its accuracy, and it may be incomplete or condensed. The report and the related FactSet sourced information are provided on an “as is” basis. The user assumes the entire risk of any use made of this information. Investors should consider the report as only a single factor in making their investment decision. The report is for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of a security. FactSet sourced information is the exclusive property of FactSet. Without prior written permission of FactSet, this information may not be reproduced, disseminated or used to create any financial products. All indices are unmanaged and performance of the indices include reinvestment of dividends and interest income, unless otherwise noted, are not illustrative of any particular investment and an investment cannot be made in any index. Past performance is no guarantee of future results.